Summary
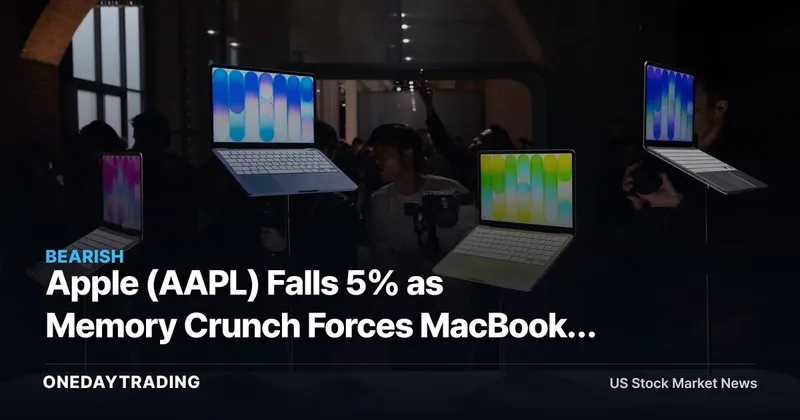
Apple shares fell about 5% after CEO Tim Cook signaled that the company will raise prices on MacBook and iPad lines to offset surging memory and storage costs. The move shifts a supply-chain cost shock onto consumers and reframes who profits from the current DRAM and NAND shortage. The clearest winners sit upstream, in memory chips, while hardware integrators absorb the margin and demand risk.
The Full Story
The selloff is less about Apple losing pricing power and more about the market repricing its cost structure. Memory and storage are commoditized inputs Apple does not make in-house, so when DRAM and NAND prices spike, Apple either eats the cost or passes it through. Cook chose pass-through, and a 5% drop says investors fear the second-order effect: higher MacBook and iPad sticker prices can soften unit demand in a category that is already replacement-cycle dependent rather than fast-growing.
The deeper signal is timing. Apple rarely telegraphs price increases mid-cycle, so an explicit cost-driven hike implies the memory squeeze is severe enough to threaten gross margins if left unaddressed. Mac and iPad together are a meaningful slice of Apple revenue outside the iPhone, and both are discretionary purchases more sensitive to price than the flagship phone.
Structural Background
Memory pricing is cyclical and supplier-concentrated. A handful of producers control most global DRAM and NAND output, and capacity that was cut during the prior downturn is now colliding with AI server demand soaking up high-bandwidth and enterprise memory. That diverts supply away from consumer devices and lifts spot prices across the board, squeezing every PC and tablet maker, not just Apple.
Stock & Sector Ripple
- AAPL — Direct subject. Faces a margin-versus-volume trade-off: passing costs protects gross margin but risks weaker Mac and iPad units, the exact tension the 5% drop reflects.
- MU (Micron) — Primary beneficiary. As a major DRAM and NAND supplier, rising memory prices expand its pricing power and revenue per bit during the shortage.
- WDC / STX — Storage suppliers gain from the same NAND and drive-cost upcycle feeding the crunch Apple cited.
- DELL / HPQ — PC peers face identical input inflation and must also raise prices or compress margins, so the read-through is industry-wide, not Apple-specific.
Bull vs Bear Scenarios
Bull case: Apple's brand strength and locked-in ecosystem let it pass costs with limited unit loss, so the hike defends margins and the 5% dip overstates real demand damage. Bear case: discretionary buyers delay upgrades, Mac and iPad volumes slip, and if memory prices keep climbing the next round of hikes deepens the demand hit while rivals undercut on price.
Investor Action Points
- Watch Apple's next quarterly Mac and iPad revenue and unit commentary for evidence the hikes are denting demand versus protecting margin.
- Track DRAM and NAND spot pricing and Micron's guidance as the leading tell on how long the cost pressure lasts.
- Compare Dell and HP pricing actions to gauge whether this is an Apple problem or a sector-wide margin squeeze.
- Monitor Apple gross margin guidance against the cost pass-through to see which side of the bull-bear split is winning.
Market data check: AAPL
AAPL last traded near $277.89 (-5.18%). Our composite signal — blending price momentum and news flow — reads 🟡 neutral. Price momentum scores 9/100 (soft).
Data as of publication. Price via market feeds; for reference only, not investment advice.
📊 Analysis
Signal Bearish
Why Apple fell 5% as cost-driven price hikes raise margin and consumer-demand risk for its Mac and iPad lines.
Tickers$AAPL$MU$DELL$HPQ$WDC
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)