At a Glance
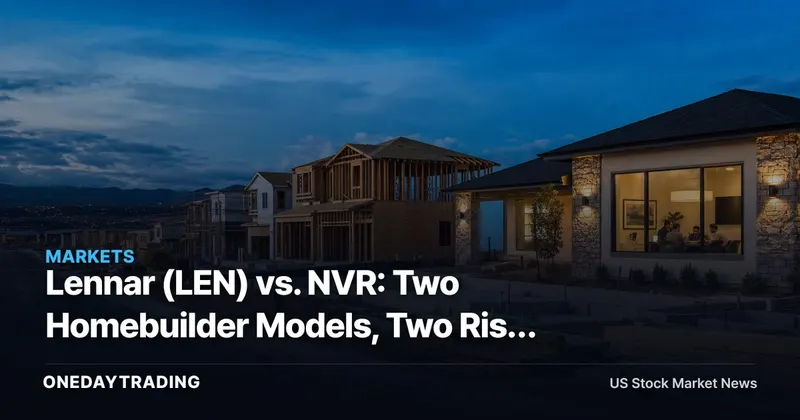
Lennar and NVR sell the same product — new homes — but run opposite playbooks. Lennar leans on national scale and an integrated financial-services arm that captures mortgage and title revenue across the buying process. NVR runs a land-light model that trades scale for return on capital. For investors, the choice is less about who builds more houses and more about which balance sheet survives a higher-for-longer rate path.
Why It Matters Now
Homebuilder economics in 2026 hinge on one variable above all: the mortgage rate the buyer actually pays. Lennar's structural answer is vertical integration. By originating mortgages and selling title and closing services in-house, it monetizes the transaction beyond the slab and the framing, and it can deploy rate buydowns as a targeted incentive to keep contracts closing when affordability tightens. That financial-services engine smooths revenue but ties more capital to land and inventory.
NVR attacks the same problem from the asset side. Rather than owning large land banks, it controls lots through options and builds largely to order, which strips inventory risk off the balance sheet and lifts return on equity. The trade-off is reach: NVR is concentrated regionally and forgoes the cross-sell that Lennar's mortgage and title operations capture on every closing.
The read-through is that these are not interchangeable bets. Lennar offers breadth, incentive firepower and a fee stream that compounds with volume. NVR offers capital discipline that shines when land prices are volatile and cancellations rise. Same sector, different exposure to the cycle.
FAQ
- What separates the two business models? Lennar pairs national homebuilding with in-house mortgage and title services; NVR uses land options to stay asset-light and build mostly to order.
- Why does integrated finance matter? It lets Lennar earn on origination and closing and fund rate buydowns that protect order volume when affordability erodes.
- Why is NVR's model defensive? Optioned lots and build-to-order reduce land and inventory write-down risk, supporting higher return on capital through downturns.
- Which is more rate-sensitive? Both depend on mortgage rates and buyer traffic, but Lennar's larger owned-land position carries more inventory exposure if demand stalls.
Related Stocks & Sectors
- Lennar (LEN) — scale, incentives and financial-services cross-sell; most exposed to land-inventory swings.
- NVR (NVR) — land-light, high-return model; defensive on capital but narrower in reach.
- D.R. Horton (DHI) — the largest-volume builder, a direct read on national new-home demand.
- PulteGroup (PHM) — diversified buyer mix across entry-level and move-up segments.
- Homebuilders & Real Estate — the group trades on mortgage rates, existing-home supply and affordability.
What to Watch
- New-order growth and cancellation rates in the next quarterly reports for both builders.
- Gross margin direction as rate-buydown incentives compress price realization.
- The 30-year mortgage rate and the 10-year Treasury yield as affordability gauges.
- NVR's return on equity versus Lennar's, the cleanest test of the model gap.
Overall Outlook
The bull case for Lennar rests on scale and a fee engine that turns every closing into multiple revenue lines, with incentive tools to defend volume. The bull case for NVR is durability: a model engineered to protect capital when land and demand turn. The shared risk is the macro — sticky mortgage rates and stretched affordability can throttle traffic regardless of who builds smarter. Investors are really choosing between offense and defense in the same housing cycle, and the rate path decides which one pays.
Market data check: LEN
LEN last traded near $93.52 (-0.36%). Our composite signal — blending price momentum and news flow — reads 🟡 neutral. Price momentum scores 47/100.
Data as of publication. Price via market feeds; for reference only, not investment advice.
📊 Analysis
Signal Neutral
Why A comparative analysis of two homebuilder business models rather than a directional catalyst, with offsetting strengths and shared rate-driven risk.
This article was independently written by OneDayTrading from public reporting. Read the original (NASDAQ)