What Changes
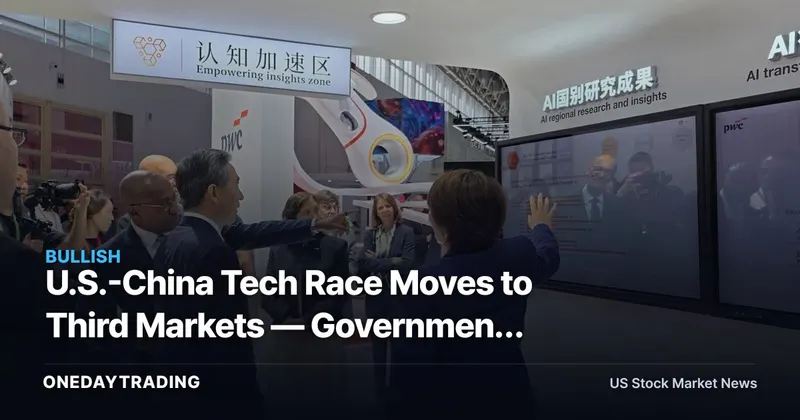
The bilateral framing of U.S.-China tech competition has consistently undersold the strategic endgame. Export controls and tariffs define the floor of rivalry; the ceiling is which nation's technology ecosystem becomes the default infrastructure across emerging economies in Asia, the Middle East, Africa, and Latin America. Both governments have reached that conclusion simultaneously, and policy support is now being deployed as a commercial accelerant — not merely a defensive barrier. That is the shift investors need to price.
For U.S. tech companies, state-backed market access compresses what would otherwise require years of relationship-building, local regulatory clearance, and capital-intensive infrastructure commitments. The complication is symmetrical: Chinese competitors receive equivalent or larger support from Beijing, particularly in markets where Chinese infrastructure financing has a multi-year head start. Commercial competition alone cannot quickly undo entrenched supply-chain and financial relationships — which means the policy tailwind for U.S. companies is real but not sufficient on its own.
By the Numbers
The source does not disclose specific capital deployment figures or market-share data, but the mechanism is directionally clear. Government-endorsed tech contracts in developing markets carry a different durability profile than purely commercial wins: harder to displace, carrying implicit sovereign backing, but also exposed to diplomatic risk in ways that arm's-length commercial agreements are not. The investment question is not whether this trend is real — the simultaneous, policy-supported expansion by both sides confirms it is — but whether valuations already embed the upside without adequately weighting the execution risk of competing on politically contested terrain.
Winners & Losers
- NVDA — The global AI infrastructure race is precisely the terrain where Nvidia holds an asymmetric advantage; U.S. policy support for tech partners in third markets directly expands the addressable market for data-center GPUs and AI training workloads in regions that have not yet committed to an architecture.
- MSFT — Microsoft Azure and its integrated AI suite represent the most complete U.S. sovereign cloud offering; government-to-government tech diplomacy maps directly onto Azure's public-sector expansion playbook in emerging economies, where multi-year infrastructure agreements drive durable revenue.
- GOOGL — Google Cloud gains a policy tailwind if U.S. diplomatic support accelerates data-center approvals abroad; the risk is that regulatory constraints in some jurisdictions limit Alphabet from the most preferential government partnership structures available to competitors.
- QCOM — Qualcomm's wireless chip position in developing-market handset supply chains faces displacement risk from Chinese alternatives; active U.S. policy support for tech partners in third countries reduces the probability of that substitution and protects a revenue base that is often overlooked in the AI-infrastructure narrative.
Risk Check
- Policy continuity: Government-backed expansion programs rotate with administrations and diplomatic cycles; commercial infrastructure built on political momentum is exposed when relationships shift.
- Third-country leverage: Nations aware they are courted by both superpowers may extract concessions from both sides without granting exclusivity — delaying the ecosystem lock-in that underpins the investment thesis.
- Chinese incumbency: In several high-priority growth regions, Chinese infrastructure investment carries a years-long lead that policy support helps U.S. companies contest but does not automatically overcome.
- Valuation absorption: U.S. large-cap tech already trades on multiples that embed strong international growth expectations; government-backed tailwinds may not shift consensus estimates if incremental international revenue falls within the existing forecast range.
Bottom Line
This is a structural shift, not a cycle — the competition for ecosystem lock-in in developing economies will compound over years, not quarters, and the entrance of government policy as an explicit competitive instrument changes the odds for U.S. chip and cloud leaders in a way that purely commercial analysis misses. The counter-scenario deserves equal weight: sovereign clients who use superpower rivalry to avoid commitment, diplomatic relationships that reverse on short notice, and Chinese competitors who out-execute on cost in price-sensitive markets. The metric to track is not the announcement of government partnerships but their conversion rate into binding, multi-year commercial infrastructure contracts — that gap between political narrative and signed order flow is where the actual earnings impact lives.
Market data check: NVDA
NVDA last traded near $194.97 (+1.27%). Our composite signal — blending price momentum and news flow — reads 🟡 neutral. Price momentum scores 60/100 (firm).
Data as of publication. Price via market feeds; for reference only, not investment advice.
📊 Analysis
Signal Bullish
Why Government policy support accelerates U.S. tech-company expansion into high-growth third markets, widening the addressable market for chip and cloud leaders and reducing ecosystem displacement risk from Chinese competitors.
Tickers$NVDA$MSFT$GOOGL$QCOM
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)