Palo Alto Networks Earnings and the Applied Compute Bet
Palo Alto Networks shares rose 6% on Thursday after the cybersecurity company beat Wall Street’s fiscal first-quarter estimates, increased its full-year guidance and announced an agreement to acquire Applied Compute. The investor message is constructive: strong reported growth now sits beside a much larger attempt to extend the company’s reach into customized open-weight models.
CNBC reported that Palo Alto Networks’ fiscal first-quarter revenue increased 39% from a year earlier. The combination of an earnings beat, faster revenue and higher guidance supports the positive stock reaction, while the acquisition introduces a separate question about how much of the longer-term opportunity can become recurring security revenue.
The distinction matters. The quarterly result describes performance already delivered; the Applied Compute transaction points toward a future business contribution that remains conditional. Investors therefore have evidence for current operating momentum, but only a company target for the deal’s eventual revenue impact.
Why the $4.5 Billion Applied Compute Deal Changes the Debate
Palo Alto Networks announced a $4.5 billion deal to buy Applied Compute, which helps train customized open-weight models. In this event, open-weight model training is the capability supplied by Applied Compute and the strategic expansion that Palo Alto Networks is seeking beyond its established cybersecurity business.
The acquisition creates a direct link between model training and security capability. If that combination proves commercially useful, Palo Alto Networks could participate in a broader customer workflow instead of addressing security as an isolated layer. That is an analytical scenario, not a reported outcome: the available evidence establishes the acquisition and Applied Compute’s function, not customer adoption or completed integration.
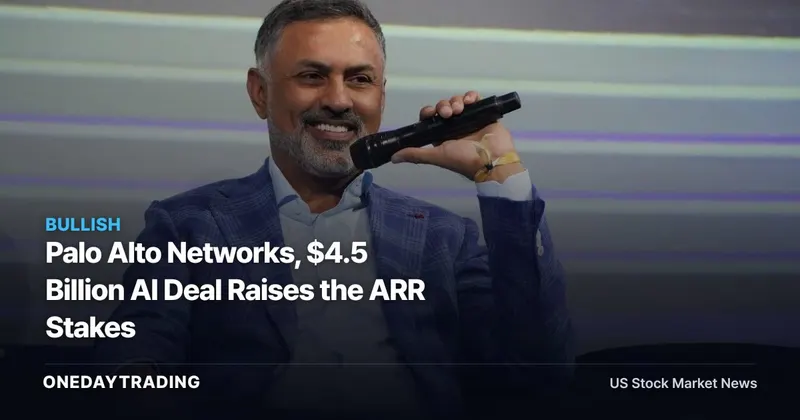
Chief Executive Nikesh Arora framed the ambition as delivering secure compute and security capability through a single relationship. His language sets a broad strategic direction, although it does not establish the economics of the combined offering. The investment case will depend on whether that direction produces durable recurring revenue rather than merely widening the company’s product narrative.
The ARR Target Is the Deal’s Critical Measurement
Palo Alto Networks expects the Applied Compute deal to add more than $1 billion in annual recurring revenue to its next-generation security business by the 2029 fiscal year. Annual recurring revenue, or ARR, is the company’s stated recurring-revenue measure for the expected contribution, making it the clearest disclosed bridge between the acquisition price and the proposed commercial result.
That target gives investors a concrete future checkpoint, but it is not revenue already achieved. The company must still translate Applied Compute’s model-training capability into an offering that supports the stated recurring-revenue contribution. Without interim figures in the supplied evidence, the path between the $4.5 billion transaction and the more-than-$1 billion ARR expectation cannot yet be evaluated.
The timing also separates the quarterly catalyst from the acquisition thesis. Fiscal first-quarter revenue growth and higher guidance belong to the current operating picture. The ARR expectation belongs to the 2029 fiscal year, so treating both as equally established would overstate what the announcement proves.
What the 6% Share Move Appears to Price
The 6% Thursday rise in Palo Alto Networks shares followed several positive disclosures at once. The earnings beat, 39% year-over-year revenue growth and increased guidance give investors reported reasons to reassess the company’s near-term trajectory. The Applied Compute announcement adds optionality, though the fact sheet does not divide the stock move among those catalysts.
The market reaction can reasonably be read as approval of the combined package rather than proof that the acquisition will succeed. A share-price increase records investor demand on Thursday; it does not validate the future ARR target, integration process or economics of the transaction. Those require later operating evidence.
This is where the story diverges from the stock move. The reported quarter supplies a performance baseline, while the deal expands the range of possible future outcomes. A successful combination could strengthen the recurring-revenue case; weak conversion from capability to customer spending could leave the acquisition’s strategic reach ahead of its measurable contribution.
Cybersecurity Context Without an Unsupported Causal Claim
The cited outages involved Microsoft and the Federal Aviation Administration, and U.S. officials had not detected malicious activity in those disruptions. That finding is important because operational outages and malicious cyber incidents are not interchangeable. The events may heighten attention to resilience, but the supplied facts do not establish that attacks caused the outages or that they directly produced Palo Alto Networks’ quarterly growth.
Arora argued that customers need strong market participants to support them because cybersecurity is “no longer child’s play,” according to CNBC. His comment expresses management’s assessment of the stakes. It should be read as strategic framing, separate from the confirmed financial evidence of an earnings beat, revenue growth and increased guidance.
The acquisition nonetheless places model training closer to the center of the company’s strategy. The relevant investor question is not whether artificial intelligence carries security concerns in the abstract; it is whether Palo Alto Networks can turn Applied Compute’s specialized capability into the recurring revenue included in its stated target.
Bull and Bear Cases for Palo Alto Networks
Bull case: The reported business entered the announcement with an earnings beat, 39% fiscal first-quarter revenue growth from a year earlier and higher full-year guidance. Applied Compute could extend that momentum if its customized open-weight model training becomes part of a differentiated secure-compute offering and contributes more than $1 billion in annual recurring revenue by the 2029 fiscal year.
Bear case: The $4.5 billion deal carries substantial unanswered questions in the available evidence. The transaction terms beyond its stated value, expected closing date, required regulatory or shareholder approvals, and Applied Compute’s current revenue and valuation details are not supplied. Fiscal first-quarter revenue, profit and earnings-per-share amounts are also unavailable, limiting a fuller assessment of the quarter and the acquisition’s financial burden.
The balanced reading is therefore positive on the disclosed operating direction and cautious on execution. Current results support the bullish sentiment; the acquisition’s future contribution still rests on a management expectation whose progress must be demonstrated over time.
Investor Checkpoints After the Applied Compute Announcement
- Next earnings report: Check whether Palo Alto Networks continues to support its increased full-year guidance and whether reported performance remains consistent with the fiscal first-quarter beat.
- Revenue growth: Compare the next disclosed growth rate with the confirmed 39% fiscal first-quarter increase from a year earlier, without assuming that one quarter establishes durability.
- Transaction disclosures: Look for the closing timetable, additional deal terms and any required approvals, since those details are absent from the available evidence.
- ARR progression: Require measurable evidence connecting Applied Compute to the expectation of more than $1 billion in annual recurring revenue for the next-generation security business by the 2029 fiscal year.
The next decisive evidence will come from execution disclosures, not another broad statement of ambition. Palo Alto Networks has established current momentum and a defined ARR objective; investors now need milestones showing how the acquired capability moves from customized open-weight model training into recurring security revenue.
📊 Analysis
Signal Bullish
Why The earnings beat, 39% revenue growth, raised guidance and a 6% share-price gain form a positive signal, tempered by uncertainty around the Applied Compute acquisition.
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)