Williams-Sonoma’s housing test is now a margin story
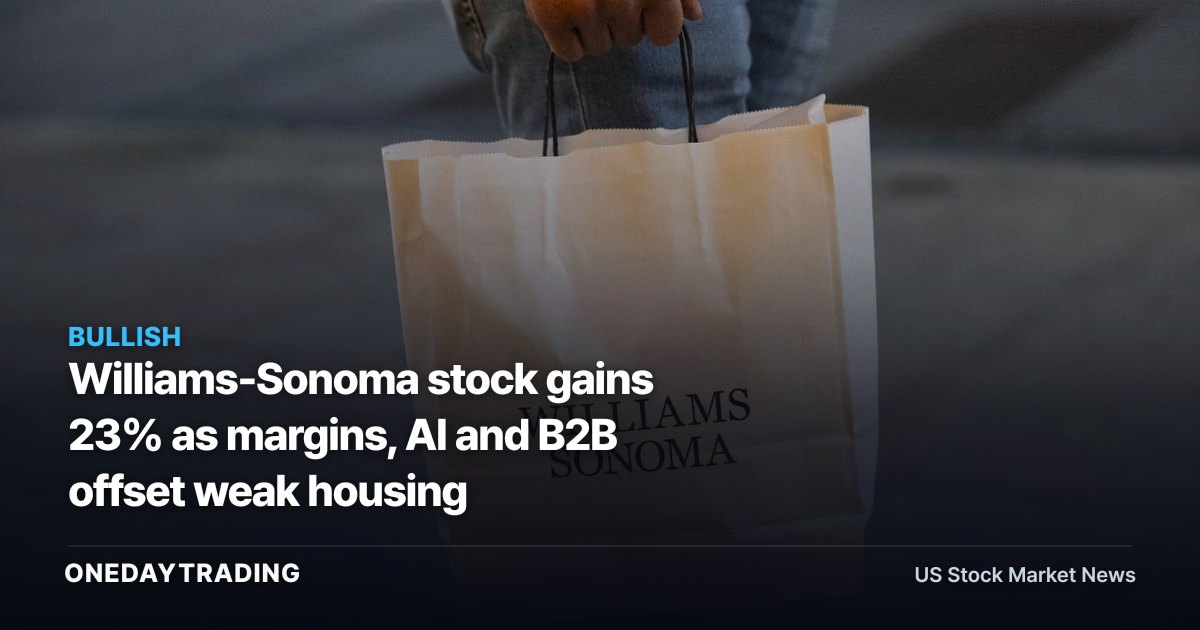
Williams-Sonoma shares had climbed about 23% year to date as of Friday, according to CNBC, outperforming the S&P 1500 Home Furnishings index and competitors including Wayfair, Arhaus, Ethan Allen and RH, formerly known as Restoration Hardware. The market is rewarding a retailer that has improved profitability and broadened demand sources while its core U.S. housing backdrop remains weak.
That distinction matters for investors. The company generates 96% of sales in the U.S., where high interest rates and higher energy and food costs have weighed on housing-related purchases. Yet its shares have risen more than 200% over a three-year period, indicating that the equity story has shifted from a simple home-sales recovery trade toward execution, mix and cost control.
How operating discipline changed the investment case
Williams-Sonoma includes its namesake brand, Pottery Barn and West Elm. Its operating margin rose from 7.9% in 2019 to 17.6% in 2021. During the tougher period after the Covid-fueled housing boom, Piper Sandler consumer-research head Peter Keith said the company expanded EBIT margin by more than 10% through fewer promotions and supply-chain optimization, including home deliveries.
The subsequent revenue comparison shows why that improvement matters. Revenue was $7.81 billion in 2025 versus $8.25 billion in 2021, while operating income was described as nearly the same. That combination suggests the business retained substantially more profit from each dollar of sales, a more durable support for valuation than a temporary volume surge.
Full-price selling is central to the mechanism. Keith said limiting promotions spread sales volume more evenly and produced favorable supply-chain effects that supported margin expansion. E-commerce, which accounts for more than two-thirds of sales and is generally more profitable than brick-and-mortar, gives those pricing and fulfillment decisions a larger earnings channel.
Olive and B2B add growth outside the housing cycle
The company’s AI sales assistant, nicknamed Olive, is aimed at converting digital intent into transactions. Williams-Sonoma said customers who engage with Olive make purchases at three times the rate of customers who do not. That figure is a reported conversion difference, not proof that the tool will deliver a specific future revenue gain, but it identifies a measurable operating lever in the company’s largest channel.
AI is also being used in supply-chain and delivery operations, according to chief technology and digital officer Sameer Hassan. If those applications reduce fulfillment costs while digital sales expand, the same investment can influence both revenue conversion and gross profitability. The next evidence would be continued disclosure of adoption and cost effects in company earnings updates; the supplied reporting does not provide a dollar savings figure.
Business-to-business sales provide another demand pool. The category grew nearly 15% in the most recent quarter ended in August and currently represents about $1 billion in annual sales. Williams-Sonoma sells to cruise ships, senior living and student housing, markets with purchasing decisions that are not identical to a household buying furniture for a new home. Management has said the B2B business could double over the next several years, making execution against that ambition a material variable rather than a completed result.
Pottery Barn shows the recovery is not uniform
The portfolio still carries furniture exposure. Pottery Barn revenue fell more than 15% from fiscal 2022 to fiscal 2025, and the company said it had leaned too heavily into decor to offset furniture declines during the post-Covid housing slump. That history limits the claim that Williams-Sonoma has fully escaped housing sensitivity.
More recently, Pottery Barn same-store sales rose 5.1% in the quarter ended in August. Keith called the renewed growth in Pottery Barn one of the more exciting parts of the company. For investors, the important test is whether furniture demand and store productivity can sustain that improvement while the business continues selling candles, pillows and kitchen items that are less dependent on housing transactions.
Tariffs are the clearest external earnings risk
More than 80% of Williams-Sonoma’s merchandise purchases in 2025 came from foreign manufacturers, leaving costs exposed to tariff policy. CEO Laura Alber said tariff stability would make planning easier for investors and the company. The risk is therefore less about a single reported event than about whether sourcing costs remain predictable enough to protect full-price selling and margins.
Williams-Sonoma received a $200 million tariff refund after the Supreme Court ruling in February and kept the refund separate from reported earnings figures. The company said it reimbursed vendors and contributed $10 million toward $1,000 401(k) contributions for each employee; its second-quarter earnings report put total vendor reimbursement at $47.5 million. Excluding the refund from earnings makes the underlying margin record easier to assess, but it also means investors should not treat the cash return as recurring operating profit.
Stocks, sector read-through and the next checks
- Williams-Sonoma: The direct read-through is a business model with higher operating margins, a predominantly e-commerce mix, Olive-driven conversion potential and a growing B2B channel. The countercase is that tariffs and furniture demand could pressure those gains.
- Pottery Barn and West Elm within Williams-Sonoma: Pottery Barn’s 5.1% same-store sales growth is a positive signal, but its more than 15% fiscal 2022-to-2025 revenue decline shows that brand-level recovery remains uneven.
- Wayfair, Arhaus, Ethan Allen and RH: CNBC reported that Williams-Sonoma outperformed these furnishings competitors and the S&P 1500 Home Furnishings index. The comparison establishes relative stock performance, but the supplied facts do not identify each rival’s revenue, margins or tariff exposure.
The next checkpoints are concrete: the next Williams-Sonoma earnings release should show whether Pottery Barn’s same-store momentum persists, whether B2B growth remains near 15%, and whether Olive engagement continues to correlate with a three-times purchase rate. Investors should also track tariff policy and merchandise-cost commentary because foreign-manufacturer sourcing is the most visible pressure point. No exact dates for those future disclosures are provided.
Overall outlook: operational gains versus exposure that remains
The bullish case rests on evidence already visible in the numbers: operating margin expanded from 7.9% in 2019 to 17.6% in 2021, 2025 revenue was below 2021 while operating income was nearly the same, and the company has added digital, AI and B2B mechanisms to its model. Those changes help explain why the stock advanced despite a sluggish housing market.
The risk case is equally specific. Furniture remains central to the brands, Pottery Barn’s multi-year revenue decline has not been erased by one quarter of 5.1% same-store growth, and more than 80% foreign sourcing leaves margins sensitive to tariff stability. Williams-Sonoma’s relative strength is therefore best tested through sustained full-price demand, profitable digital conversion and repeat B2B expansion—not through housing recovery alone.
📊 Analysis
Signal Bullish
Why Improved profitability, digital conversion, B2B growth and renewed Pottery Barn sales support Williams-Sonoma despite housing and tariff risks.
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)