Volkswagen’s warning turns an earnings reset into an index problem
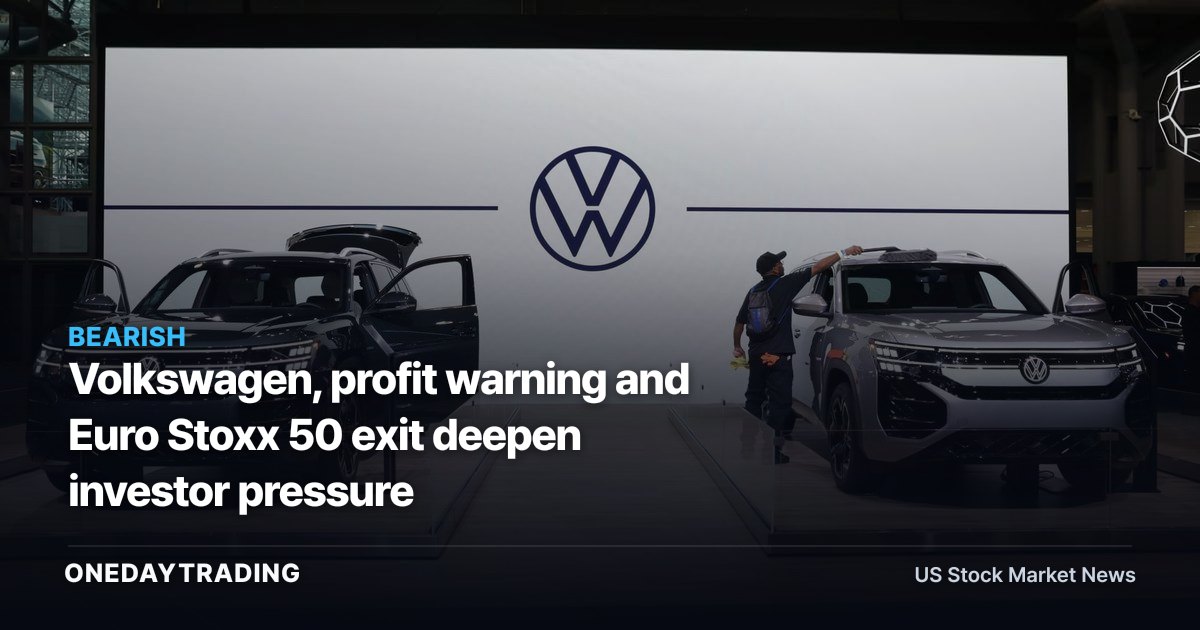
Volkswagen’s latest profit warning is a bearish signal for autos because it combines a sharp reduction in expected profitability with a loss of Euro Stoxx 50 membership. On Sept. 21, 2026, the company said it now expects a 1% operating return on sales, down from a previous forecast range of 4% to 5.5%; its shares were 0.5% lower in mid-morning deals after an 8.3% fall on Friday, according to CNBC’s report. The immediate investor question is whether the 10 billion euros of one-off effects explain most of the damage or whether the underlying business is also losing earning power.
The index exit matters because it removes Volkswagen from a benchmark tracking 50 major euro-area companies. Nokia replaced it. Index membership does not change factories, brands or cash flows, but the change reinforces the market’s judgment that Volkswagen has lost relative standing while the European auto sector faces a difficult transition.
The guidance cut is large, but its composition is mixed
Volkswagen attributed the warning to an impairment connected with its large Porsche holding, further deterioration in the market environment, particularly in China, and restructuring expenses. The company also said an accelerated shift in demand toward battery-electric vehicles would leave developments below original expectations, especially for the Audi and Volkswagen Passenger Cars brands.
Those disclosures combine balance-sheet pressure, regional weakness and product-transition risk. An impairment can reduce reported earnings without matching cash leaving the business immediately, while restructuring expenses can front-load costs before any efficiency benefit appears. The fact that the update includes 10 billion euros in one-off effects hitting earnings this year therefore makes the headline forecast change harder to read as a pure measure of recurring operating performance.
The precise amount of the Porsche-related impairment is not provided, and the timing and completion status of the planned job cuts are also unspecified. That limits how confidently investors can separate temporary accounting and restructuring charges from a durable decline in operating returns.
Why the 1% forecast matters for the brands
Operating return on sales measures how much operating profit a company generates from each unit of revenue. Moving from a prior 4% to 5.5% forecast range to 1% leaves much less room for production costs, pricing pressure and transition spending to be absorbed while preserving profit.
Volkswagen’s own explanation points to demand moving faster toward battery-electric vehicles than earlier expectations assumed. Audi and Volkswagen Passenger Cars are specifically exposed in the company’s warning, so the issue is not only a group-level accounting adjustment. It is also a question of whether the brand mix and manufacturing footprint can adapt quickly enough to changing customer demand.
China is another transmission channel. Volkswagen identified a worsening market environment there, but the supplied report does not quantify the regional revenue or profit effect. Investors therefore have a clear direction of risk but not a disclosed measure of how much China accounts for the downgrade.
Deutsche Bank offers a less severe underlying reading
Deutsche Bank analysts said the warning “initially looks severe,” but argued that it “significantly overstates the deterioration in the underlying business.” Their note said underlying margins remain around 4% and cash generation remains intact, despite the 10 billion euros of one-off effects scheduled to hit earnings this year.
That view creates the central tension in the stock. Reported earnings are facing a substantial hit, while the analysts’ assessment suggests recurring profitability and cash generation have not collapsed to the same extent. The market must decide how much weight to place on the current-year charges and how much on the lower forecast for operating return on sales.
The countercase is that a 1% group forecast may still signal pressure beyond the disclosed one-offs. Volkswagen cited China, restructuring and the electric-vehicle demand shift in the same update, and the report does not establish when those pressures will ease. Cash generation remaining intact is supportive, but it does not by itself restore the previous operating-return outlook.
What the share move and index exit are pricing
- Volkswagen: Shares fell 0.5% in 2026-09-21 mid-morning deals after declining 8.3% on Friday. The stock is down 27.5% this year and near its lowest level since 2010, showing that investors had already been marking down expectations before the latest warning.
- Euro Stoxx 50 exposure: Volkswagen’s removal from the 50-stock index and replacement by Nokia creates a visible benchmark-status setback. The change is an index classification, not evidence of an additional operating loss, but it can intensify scrutiny of Volkswagen’s relative performance.
- Stellantis: The Jeep and Dodge maker fell out of the blue-chip index a year ago amid its own challenges and restructuring. That parallel places Volkswagen’s exit within a broader European autos-sector pattern, without proving that the companies face identical financial outcomes.
- Nokia: Nokia’s replacement of Volkswagen reflects the index update’s reallocation across major sectors. The supplied facts identify Nokia as the incoming constituent but do not quantify any index-flow effect on either company.
Restructuring is a test of execution, not yet a result
Volkswagen has approved the next stage of a restructuring and streamlining effort expected to cut 100,000 jobs. That scale indicates management is pursuing a substantial cost and capacity response to waning profits and the electric-vehicle transition.
The plan’s economic value depends on execution: how quickly costs are removed, how restructuring charges are absorbed and whether the remaining organization can support demand for battery-electric vehicles. The facts supplied do not provide a completion timetable, annual savings target or a measure of production capacity affected. Investors should treat the job-cut figure as a plan parameter, not as achieved earnings improvement.
Investor checkpoints after the warning
- Operating-return guidance: Check whether Volkswagen maintains the 1% forecast or changes it again, and whether management distinguishes recurring operating performance from the 10 billion euros of one-off effects.
- Underlying margins and cash: Compare subsequent disclosures with Deutsche Bank’s assessment that underlying margins remain around 4% and cash generation remains intact.
- China and brand commentary: Look for new evidence on the deteriorating Chinese market environment and on Audi and Volkswagen Passenger Cars, the brands named in the warning.
- Restructuring delivery: Track concrete progress toward the planned 100,000-job reduction, while recognizing that the exact timing and completion status are not provided in the current report.
Outlook: a damaged multiple with one stabilizing argument
The bearish case is straightforward: Volkswagen has cut its operating-return forecast to 1%, cited several simultaneous pressures and lost Euro Stoxx 50 membership after a 27.5% share-price decline this year. The combination suggests that investors are confronting both a near-term earnings hit and uncertainty over the group’s ability to adapt its brands and cost base.
The stabilizing argument comes from the quality of the charge. Deutsche Bank’s view that underlying margins remain around 4% and cash generation remains intact means the reported earnings impact may overstate the deterioration in ongoing operations. That interpretation becomes more credible if future updates show the one-off effects contained, cash preserved and the restructuring moving from approval toward measurable execution.
For now, the next informative evidence is not another slogan about the transition. It is whether Volkswagen can hold the 1% operating-return forecast, demonstrate that underlying margins remain near 4%, and provide clearer evidence on China, Audi, Volkswagen Passenger Cars and the 100,000-job restructuring plan.
📊 Analysis
Signal Bearish
Why Volkswagen lowered guidance, reported major one-off effects and lost Euro Stoxx 50 membership while its shares continued to decline.
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)