At a Glance: Federal Reserve Policy Meets a Housing Contraction
Federal Reserve policy is colliding with a U.S. housing market in which current mortgage rates stand at 7.43% and September activity weakened across sales, construction and permits. For real-estate investors, the central issue is no longer one disappointing indicator; it is the alignment of weaker demand signals, reduced building activity and an affordability constraint that could persist if borrowing costs do not improve.
CNBC Markets reported that the National Association of Realtors’ pending-sales index fell 7.3% month over month and 11.3% year over year in September, reaching an all-time low in records extending to 2001. Pending sales are home-purchase contracts that have been signed but not completed, making the index a forward-looking measure of transaction activity.
September Housing Data Broke Below Expectations
The pending-sales decline was far steeper than the 0.4% September drop estimated by Wall Street. That gap matters because it shows that the deterioration was not fully reflected in expectations: the reported weakness exceeded an already negative baseline rather than merely confirming it.
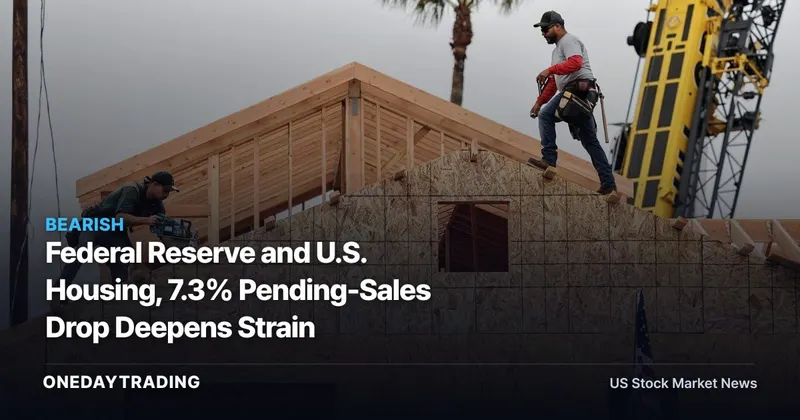
Construction data reinforced the sales signal. Privately owned housing starts declined 5.2% month over month in September against an expected 0.4% decline. Building permits slipped 0.2% during the month, missing the Dow Jones consensus outlook for a 2% gain.
The single-family segment supplied an additional warning. September single-family permits totaled 845,000, down 4% from August and at their lowest total since 2023. Permits represent an earlier stage of the construction pipeline than completed homes, so their direction provides a concrete checkpoint for whether future building activity is expanding or contracting.
Home builder sentiment was also at a low not seen in 14 years. Taken together, the sales index, housing starts, permits and sentiment indicate pressure at several points in the housing process rather than weakness confined to one reported series.
Mortgage Rates Tighten the Affordability Constraint
Mortgage News Daily reported that the 30-year mortgage rate stayed above 7% for most of September and finished the month around 7.6%. Mortgage rates had been closer to 3% five years ago, leaving a wide divide between current financing conditions and the borrowing costs attached to many existing loans.
That divide affects both sides of a transaction. Elevated rates can make a prospective purchase less affordable, while owners with cheaper existing loans face a higher financing cost if they move. Lawrence Yun of the National Association of Realtors said September conditions weakened as mortgage rates rose rapidly and argued that buyers and sellers may be waiting for more favorable rates.
The borrower distribution makes that restraint visible. More than 95% of mortgage borrowers hold rates below the prevailing level, while 65% have rates that are 2 percentage points lower. This “lock-in” effect can suppress turnover because moving may require replacing a lower-rate loan with more expensive financing.
Chris Rupkey of Fwdbonds described the condition starkly: “It is not winter yet but housing is going into a deep freeze.” The data support the warning through lower pending sales and reduced construction activity, though they do not establish when the market will stabilize or where mortgage rates will move next.
The Federal Reserve’s Policy Tension
Housing weakness might ordinarily strengthen the case for lower borrowing costs, yet the Federal Reserve is also confronting broader price pressure. The latest reported reading for wholesale final demand goods prices rose 2.6%, the fastest pace in a Bureau of Labor Statistics series beginning in December 2009.
Markets expected the Federal Reserve to hold benchmark rates steady at its next-week meeting. CME Group futures pricing nevertheless implied the possibility of a 0.25 percentage-point increase in December and another 0.25 percentage-point increase in March 2027. Futures pricing reflects market expectations, not decisions the central bank has already made.
That distinction is crucial for housing exposure. The market has incorporated the possibility of later increases, while the Federal Reserve’s actual decisions and the resulting path of mortgage rates remain unknown. Investors therefore face two separate uncertainties: whether benchmark rates rise and whether mortgage financing costs respond in the same direction.
Goldman Sachs Maps a Longer Housing Slowdown
Goldman Sachs forecast residential investment declines of 2.5%, 4% and 1%, respectively, over the coming three quarters. The sequence implies continuing contraction rather than an immediate recovery, with affordability acting as the principal headwind in the firm’s outlook.
For 2027, Goldman Sachs projected 875,000 single-family starts. It also forecast 3.9 million existing-home sales, a level 26% below pre-Covid 2019 activity. Ronnie Walker said affordability would increasingly weigh on activity in 2027 as higher mortgage rates exert their strongest pressure on housing turnover.
These projections are scenarios, not reported outcomes. Actual residential investment, starts and sales could differ, especially because the future course of mortgage rates is unresolved. Their analytical value lies in showing how sustained affordability pressure could travel from financing conditions into fewer transactions and weaker construction.
Debates That Will Determine the Next Turn
- Have mortgage rates peaked? Yun suggested rates could be topping out because mortgage costs have already risen substantially. The available evidence does not confirm whether they will rise or fall from here.
- Can limited turnover cushion prices while hurting activity? The borrower-rate gap can discourage owners from moving, restricting existing-home transactions even as affordability weighs on potential buyers.
- Will permits foreshadow deeper construction weakness? The 845,000 single-family permits recorded in September, down 4% from August, establish the next comparison point for the building pipeline.
- How much weakness can policy tolerate? Housing indicators are deteriorating while wholesale final demand goods prices rose 2.6%, leaving the Federal Reserve to assess conflicting pressures.
Real Estate Exposure Without Unsupported Stock Calls
- Residential real estate: The 7.3% monthly fall in pending sales and the all-time index low point to weaker transaction activity entering the completion stage.
- Home construction: A 5.2% monthly decline in privately owned housing starts and a 0.2% fall in permits show reduced activity and a weaker forward pipeline.
- Mortgage-linked activity: Current mortgage rates of 7.43%, combined with 95% of borrowers holding lower rates, reinforce the constraint on refinancing and housing turnover.
- Housing investment: Goldman Sachs’ projected declines over the coming three quarters frame downside risk, while any favorable movement in mortgage rates provides the principal counter-scenario.
What Investors Should Monitor Next
- The next-week Federal Reserve meeting: Compare the expected decision to hold benchmark rates steady with any change in the market’s outlook for December and March 2027.
- The 30-year mortgage rate: Test whether it moves favorably from the 7.43% current level and the roughly 7.6% level reported at the end of September.
- Pending sales: Check whether the index moves away from its record low or extends September’s 7.3% monthly and 11.3% annual declines.
- Single-family permits and starts: Use 845,000 permits and Goldman Sachs’ 875,000-start forecast for 2027 as separate benchmarks for reported activity and the longer-range outlook.
Overall Outlook: Bearish Data, Conditional Policy Relief
The housing signal is bearish because demand, construction and permits weakened together while financing remained expensive. The strongest countercase is a favorable move in mortgage rates that releases some deferred buyer and seller activity, consistent with Yun’s view that participants may be holding back rather than leaving the market permanently.
The next decisive evidence will come from the Federal Reserve’s next-week meeting, subsequent mortgage-rate readings and the next reports on pending sales, starts and permits. Stabilization requires confirmation in those measures; neither futures pricing nor a forecast can substitute for the reported path of borrowing costs and housing activity.
📊 Analysis
Signal Bearish
Why Weak pending sales, housing starts and permits point to sustained pressure on housing activity while elevated mortgage rates constrain affordability.
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC Markets)