Tesla Reassigns Texas Capacity to Cybercab
The sharp investor read is not simply that one Tesla vehicle is approaching the end of production at one plant. Management is choosing between products that share constrained physical infrastructure, and Cybercab is receiving the space currently assigned to Cybertruck. That makes the announcement a capital-allocation signal expressed through factory capacity rather than through financial guidance.
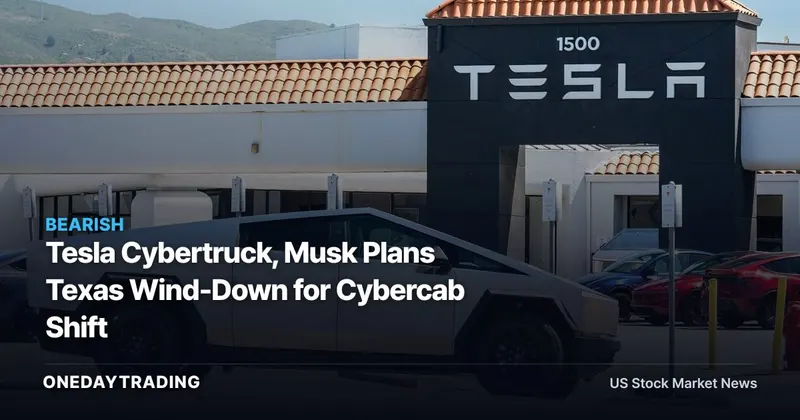
The production shift is Tesla’s plan to wind down Cybertruck output at its Texas gigafactory so that the same facility can accommodate Cybercab production. Cybertruck is produced exclusively at the Texas plant alongside the Tesla Model Y and the two-seat Cybercab. Ending output there therefore removes the vehicle’s only confirmed production location.
What happens to the product itself is less certain. Elon Musk did not say whether Cybertruck manufacturing would move to another facility, and his statement that the fleet would remain in use for a long time does not establish continued production elsewhere. Investors should separate an existing fleet from an active manufacturing program.
Cybertruck Sales Put the Capacity Choice in Context
The volume evidence explains why Tesla may prefer a different use for the plant. Cox Automotive estimated that U.S. Cybertruck sales reached 20,237 units last year, a 48% decline from 38,965 units in 2024. Tesla does not disclose sales by model or region, so those estimates cannot be reconciled with an official Cybertruck figure.
The sales trajectory also sits far below the earlier scale associated with the program. CNBC reported that Elon Musk had predicted eventual annual Cybertruck sales of 250,000 vehicles before deliveries began. Tesla started Cybertruck deliveries in late 2023, leaving the later decline as the clearest available demand indicator in the supplied evidence.
For investors, the mechanism is straightforward. A factory area devoted to a lower-volume product carries an opportunity cost when management wants to expand another vehicle on the same site. Reassigning that area could improve capacity utilization if Cybercab production develops as intended, though the facts supplied provide no Cybercab output, orders or financial contribution with which to measure that possibility.
SpaceX Purchases Complicate the Demand Signal
A SpaceX financial filing said SpaceX spent $131 million buying Cybertrucks at Tesla’s suggested retail price last year. SpaceX is described as Elon Musk’s aerospace and technology conglomerate, making the purchase relevant when assessing how broadly the truck’s reported demand extended beyond entities connected to Musk.
The filing establishes the buyer, expenditure, pricing basis and period. It does not provide enough information to calculate the number of vehicles purchased or the share of estimated Cybertruck sales represented by SpaceX. Treating the entire 20,237-unit U.S. estimate as independent consumer demand would therefore go beyond the available evidence.
This distinction matters for the Tesla stock debate because product durability depends on repeatable demand, not merely recorded deliveries. The supplied facts establish weaker estimated sales and one substantial purchaser, but they do not reveal customer mix, order depth or the economics of the Cybertruck program.
Cybertruck Recalls Add an Execution Check
The 2024 Tesla Cybertruck was subject to 11 voluntary recalls, according to the National Highway Traffic Safety Administration website. That record does not by itself quantify repair expense, customer retention or margin effects, none of which are provided. It does establish that manufacturing and product execution belong beside sales volume in any assessment of the program.
The truck’s history underscores the distance between product novelty and commercial scale. At its 2019 unveiling, Elon Musk said, “Trucks have been the same for a very long time” and “We want to try something different.” The coming Texas wind-down shows that differentiation alone did not produce the volume once envisioned for the vehicle.
Winners and Losers in Tesla’s Factory Reallocation
- Cybercab capacity: The planned beneficiary is Cybercab production because Tesla explicitly intends to make room for it at the Texas plant. The economic benefit remains conditional because no production target, order figure or financial outcome is supplied.
- Cybertruck production: The direct loser is the truck’s existing manufacturing program in Texas. Its only confirmed plant is scheduled for a wind-down around the middle of next year, with no confirmed replacement facility.
- Tesla stock: The near-term signal is bearish because estimated U.S. Cybertruck sales declined and management is withdrawing factory space from the product. A more constructive interpretation requires evidence that Cybercab can convert the released capacity into stronger output or demand.
Risks and Evidence Gaps for Tesla Investors
- Relocation uncertainty: Tesla has not confirmed whether Cybertruck production will continue at a different facility. A relocation would change the meaning of the Texas decision from a broader product exit to a site-specific transfer.
- Disclosure limits: Tesla does not report sales by model or region, leaving Cox Automotive’s U.S. estimate as the available volume benchmark rather than an official company total.
- Cybercab execution: Making factory space available does not establish production success. The next meaningful evidence is whether Tesla discloses Cybercab output, orders or another measurable indicator of demand.
- Product execution: The 11 voluntary recalls attached to the 2024 Cybertruck make future recall activity and manufacturing performance relevant checks on the remaining fleet and any potential continuation of production.
The Next Test for Tesla’s Texas Strategy
The Cybertruck decision crystallizes a difficult but rational factory question: preserve capacity for a vehicle whose estimated U.S. sales fell 48% last year, or redirect that space toward Cybercab. The bearish evidence is concrete for Cybertruck—lower estimated volume, a coming Texas wind-down and 11 voluntary recalls for the 2024 vehicle. The potential upside for Tesla remains conditional on Cybercab turning released space into measurable production and demand.
The next checkpoint is not another statement about product ambition. Investors need confirmation of whether Cybertruck moves to another facility and quantitative evidence for Cybercab as Tesla approaches the planned wind-down around the middle of next year. Until those facts arrive, the announcement supports a negative reading on Cybertruck momentum and an unproven reading on the capacity replacing it.
Market data check: Tesla, Inc.
Tesla, Inc. last traded near $351.57 (+2.29%). Our composite signal — blending price momentum and news flow — reads 🟡 neutral. Price momentum scores 68/100 (firm).
Data as of publication. Price via market feeds; for reference only, not investment advice.
📊 Analysis
Signal Bearish
Why The Cybertruck sales estimate and planned Texas production wind-down signal weak product momentum, although reallocating capacity to Cybercab could improve its future use.
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)