Why Weak Sentiment Matters for Markets
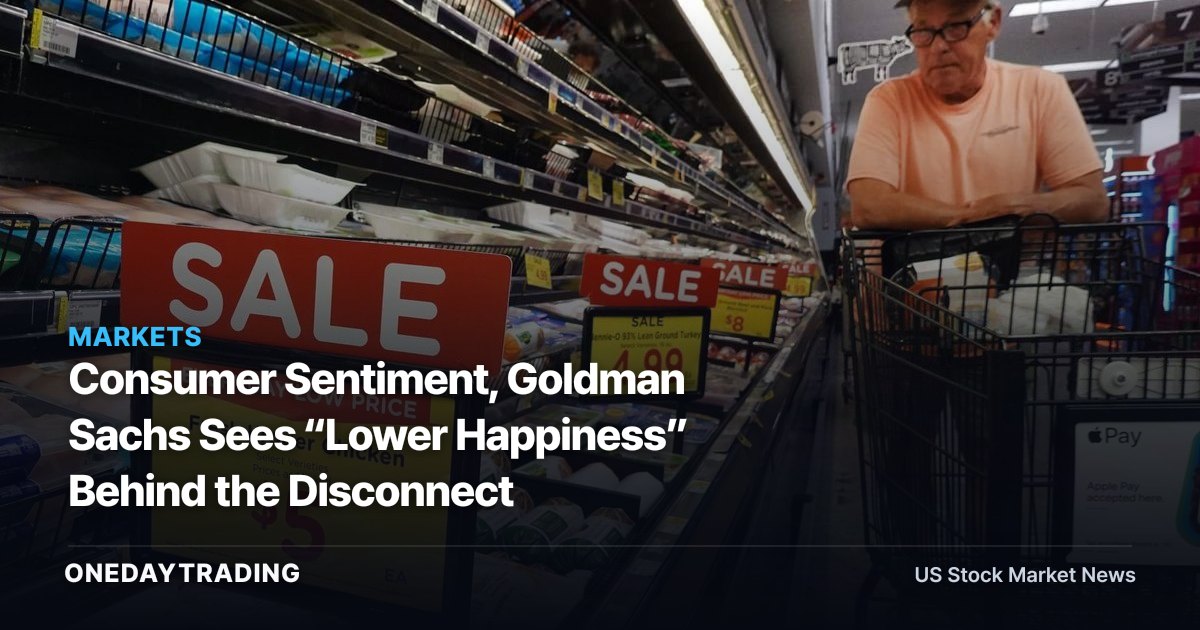
Consumer sentiment is deteriorating faster than the economic picture implied by other measures, and Goldman Sachs economist Joseph Briggs says the gap may reflect social pessimism as much as household finances. For investors, that distinction matters: if confidence is being shaped by lower happiness and trust in institutions, a strong economy alone may not restore the survey readings that markets often use to gauge future spending and growth.
The University of Michigan consumer sentiment index reached record lows this year. CNBC reported that the index fell 13% year over year in September, including a drop of almost 8% from August to September. The figures show a sharp change in reported attitudes, but they do not by themselves establish a corresponding decline in economic output or corporate earnings.
Goldman’s Explanation for the Disconnect
Briggs told clients that “low reported economic sentiment likely reflects a more fundamental, downbeat assessment of the state of the world rather than the economy.” His argument places the survey weakness partly outside conventional macroeconomic measures. Goldman Sachs also said inflationary pressures are likely hurting confidence, so the explanation is not exclusively social or institutional.
Briggs described “lower happiness” as one reason sentiment can remain depressed while other economic indicators appear stronger. He said consumer sentiment may not improve even if the economy continues to perform strongly, which would make the indicator a less useful predictor of economic dynamics. That is a conditional interpretation, not a forecast of either economic growth or market performance.
What the Happiness Data Shows
The University of Chicago General Social Survey provides the comparison Briggs used to frame the shift. The share of respondents reporting that they felt “very happy” was 31% in 2016 and 23% in 2024. Over the same period, the share saying they were “not too happy” increased from 13% to 20%.
Those figures indicate that happiness did not fully recover from its pandemic-era decline. Briggs said overall happiness fell more sharply than the survey’s measure of financial satisfaction, suggesting that household sentiment cannot be reduced to perceptions of personal finances alone. The specific causes of the happiness decline are not provided in the reporting.
Trust in Institutions Adds Another Layer
Joanne Hsu, director of Michigan’s survey, told CNBC that the sentiment downtrend mirrors decreases in both happiness and trust in public institutions. Her observation supports the idea that survey responses may capture broader views about society, not only evaluations of income, prices or employment.
Briggs linked lower trust in institutions to a “disproportionate amount” of the decline in net happiness in recent years. That relationship helps explain why sentiment could remain weak even when the economy performs well on paper. It does not identify which institutions are responsible or establish a single cause for the change.
Market and Sector Read-Through
- Consumer-facing sectors: Persistently weak confidence could complicate interpretation of future spending signals because sentiment may not move in line with economic performance. The facts supplied do not identify particular retailers, brands or companies as winners or losers.
- Broad equity markets: Investors may place less weight on the University of Michigan index if Briggs’s view proves correct and non-economic variables keep the reading depressed. That is an analytical implication, not a reported change in valuation or market direction.
- Financial conditions: Inflationary pressure remains a separate factor Goldman Sachs identified as damaging confidence. Without additional data, the relative contribution of inflation and lower happiness cannot be quantified.
Investor Checkpoints
- Track whether the University of Michigan consumer sentiment index continues to set record lows or stabilizes after its 13% year-over-year September decline.
- Compare the monthly direction of sentiment with other economic measures rather than assuming the survey alone captures household conditions.
- Watch whether future commentary from Goldman Sachs or Michigan’s survey team continues to connect sentiment with happiness and institutional trust.
- Assess whether inflationary pressures remain a stated drag on confidence, since Goldman Sachs identified them as an additional influence.
What Changes the Interpretation
The constructive case is that sentiment is being depressed by attitudes that may not map directly onto economic activity. If the economy continues to perform strongly, weak survey readings could eventually become less informative about actual economic dynamics, as Briggs suggested.
The risk is that inflationary pressure and low confidence reinforce each other, leaving the index weak even alongside solid economic performance. The available reporting provides no forecast for future sentiment or economic growth, so investors must treat any improvement or deterioration as an observable development rather than a predetermined outcome.
Outlook for Consumer Confidence
The central issue is whether the University of Michigan index begins to recover or remains disconnected from the broader economic picture. A sustained gap would challenge the usual use of consumer sentiment as a forward-looking signal, while a renewed decline would keep the question of inflation, happiness and trust unresolved.
The next useful evidence is the subsequent University of Michigan reading and any updated interpretation from Briggs or Hsu. Those observations can show whether September’s 13% year-over-year decline was part of an ongoing pattern or another extreme reading in a sentiment series already described as being at record lows.
📊 Analysis
Signal Neutral
Why The report describes a structural explanation for weak consumer sentiment but provides no confirmed earnings, policy or stock-market catalyst.
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)