Dreamforce’s practical AI test
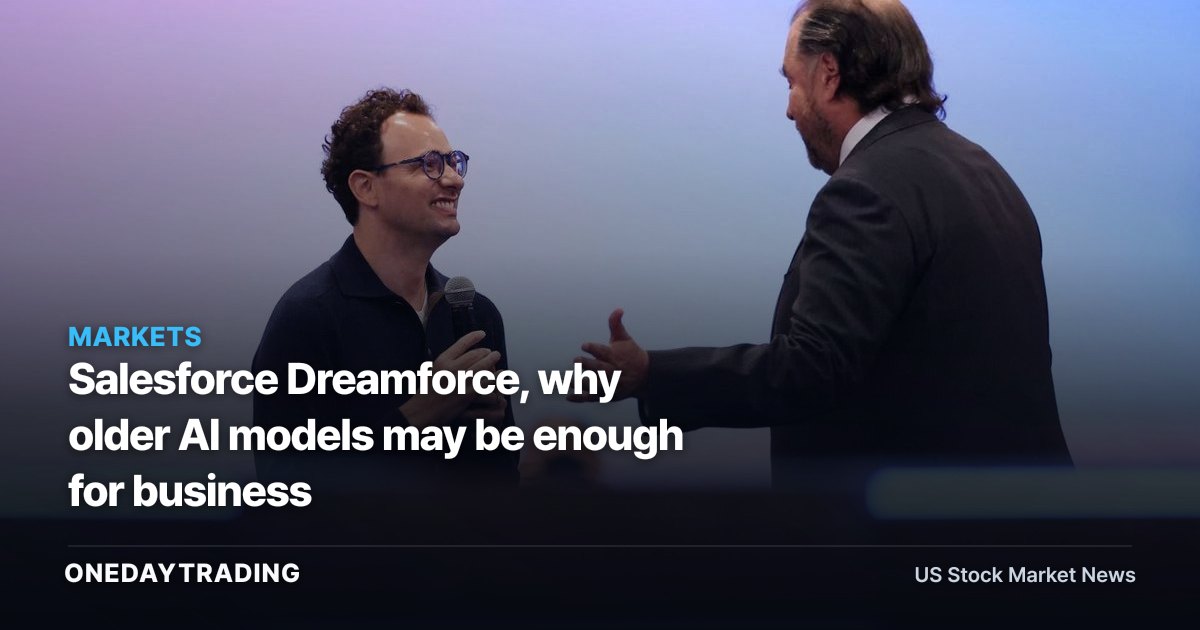
Salesforce’s 50,000-person Dreamforce conference in San Francisco exposed a split that matters for software investors: executives debated AI safety and development speed, while customers focused on whether existing, cheaper models already solve their daily work. The implication for Salesforce and its software peers is less about a race to the newest model than about deploying useful agents at a cost customers will accept.
CNBC reported on September 18, 2026, that keynote conversations included Salesforce CEO Marc Benioff and the leaders of Anthropic, OpenAI and Nvidia. Nvidia CEO Jensen Huang urged frontier laboratories to “run as fast as you can.” On the conference floor, however, attendees described a more measured adoption curve. Alec Bronston of retail data company Spins said, “It’s already hard enough to keep up,” suggesting that a slower release cycle could give customers time to learn how to use systems already available.
Agentforce is being judged on workflow, not novelty
Agentforce is Salesforce’s set of tools for responding to customer-service questions and sales inquiries. A Salesforce support page says those tools are not relying on Anthropic’s Claude Fable 5.1 or OpenAI’s GPT-6 Astra, although the company does not specify which model handles each workload. That limitation matters: investors can observe the product’s function, but cannot map every Agentforce task to a named model from the available evidence.
Customers and partners at Dreamforce told CNBC that older and cheaper models are sufficient for many routine sales and customer-service jobs. Tim Sanders, chief innovation officer at software-review company G2, said, “The majority of agentic outcomes aren’t driven by frontier capabilities.” Kevin Lee, technology chief at Nice, made a similar point, saying current models and even one generation behind are effective for customer needs and that “everything beyond this point is icing on the cake.”
That view creates a practical adoption path for Salesforce. Companies still determining their AI budgets can begin with established systems, measure whether agents resolve inquiries or assist sales teams, and delay a move to more expensive frontier models. The evidence does not establish how many Dreamforce attendees held that view, so it should be read as a customer and partner signal rather than a market-wide survey.
The cost curve changes the SaaS model
AI introduces a variable-cost layer into software. A token represents about three-quarters of a word, and cloud software companies must account for the amount of model usage and the complexity of the requested output. Sanders said a typical SaaS model can carry gross margins of 85%, while an agentic model could bring margins closer to 45% because each interaction consumes model capacity.
This mechanism puts the emphasis on routing and workload design. Docusign uses both frontier and open-weight models, reserving larger systems for judgment-intensive tasks such as complex clause analysis, multi-document reasoning and summarization. CEO Allan Thygesen said Docusign uses model routing to direct each request to the most cost-effective AI system. For software vendors, the commercial question is therefore not simply whether an agent works, but whether the provider can match the model to the task without allowing usage costs to overwhelm revenue.
Salesforce customers’ preference for adequate, lower-cost models could help protect that equation in routine service workflows. It could also limit the immediate differentiation of the most advanced models in standard SaaS applications. The counterpressure is that customers may still demand frontier capability for complex reasoning, and the available evidence does not provide Salesforce’s model-by-model costs or margins.
Frontier capability still has a place
Dreamforce did not show that frontier models are irrelevant. Databricks released GPT-6 Astra to all 3,500 of its software developers this week. Engineering vice president Patrick Wendell wrote that Astra “unambiguously out performs our previous highest-end models (Opus 5, Sol 5.6) on highly complex tasks.” That is a different workload from routine customer-service responses: the value proposition is concentrated in difficult engineering and reasoning tasks where capability can matter more than per-call cost.
Nagarro illustrates another purchasing pattern. Technology chief Ram Reddy said its engineers wait about three months before integrating the latest models from AI laboratories. The delay indicates that integration, testing and operating discipline can be as important as launch timing for service providers. It also provides a counterweight to Huang’s call for frontier labs to accelerate: a faster model release does not automatically produce faster enterprise adoption.
Anthropic and OpenAI remain part of Salesforce’s ecosystem discussion. Salesforce’s Claudeforce gives salespeople access to critical data from inside Anthropic’s Claude chatbot, while Agentforce handles sales and customer-service use cases. These relationships expand the available tools, but the fact sheet does not identify which model Salesforce uses for each Agentforce task or quantify revenue from Claudeforce.
What the signal means for software stocks
- Salesforce (CRM): The company’s customer base is signaling that older models may be sufficient for many Agentforce workloads, which could support adoption where buyers are sensitive to operating cost. Salesforce shares are down 8% this year according to the article, but the evidence does not provide a specific cause for that move. The stock’s read-through therefore depends on whether Agentforce expands usage without creating an unfavorable cost burden.
- Docusign (DOCU): Model routing and a mix of frontier and open-weight systems give Docusign a documented way to reserve expensive capability for complex document work. Investors should focus on whether that architecture allows the company to add AI functionality while keeping the variable cost of each request aligned with customer value.
- Cloud software sector: The margin framework is the central sector issue. A shift from an 85% typical SaaS gross-margin structure toward 45% for agentic models would make model selection, token consumption and pricing design material operating metrics. The figures are a general framework cited by Sanders, not company-specific forecasts.
- Databricks and AI infrastructure demand: Databricks’ decision to provide GPT-6 Astra to 3,500 developers demonstrates willingness to pay for frontier performance in complex work. It does not establish that every software company will follow the same path, particularly when Nagarro waits about three months before integration.
Bull and bear cases after Dreamforce
The constructive case is operational. If established models can handle most sales and service interactions, Salesforce and similar vendors may expand agent deployment without forcing customers into the highest per-call costs. Docusign’s routing approach shows how a provider can combine model quality with cost control, while the practical tone from customers suggests a larger pool of enterprises may be able to begin adoption.
The risk case is economic and competitive. Agentic products could lower gross margins from the typical 85% SaaS level toward 45% if usage rises faster than pricing or efficiency. Frontier laboratories may also continue to improve quickly, requiring vendors to retest systems and customers to revisit budgets. Databricks’ broad Astra rollout shows that some users value maximum capability, while the 8% decline in Salesforce shares this year indicates that investor confidence is not guaranteed by conference enthusiasm.
Safety and release speed add another uncertainty. Huang argued for faster development, while Anthropic’s Dario Amodei and OpenAI’s Sam Altman discussed safety initiatives and a slower pace after concerns raised by an Anthropic researcher. Those positions shape the model supply available to enterprise vendors, but the supplied evidence does not establish a regulatory outcome or a direct financial effect.
Investor checkpoints from the event
- Track Salesforce disclosures on Agentforce adoption and usage economics, while recognizing that the available evidence does not identify the model assigned to each workload.
- Watch whether software vendors describe model routing, token consumption and gross-margin effects as AI usage scales; the 85% versus 45% framework shows why those metrics matter.
- Compare frontier-model deployment with integration lags: Databricks gave GPT-6 Astra to 3,500 developers this week, while Nagarro waits about three months before plugging in new models.
- Separate routine automation from judgment-intensive work. Docusign’s use of larger models for complex clause analysis and multi-document reasoning provides a concrete example of where frontier capability may still command spending.
📊 Analysis
Signal Neutral
Why Dreamforce showed practical demand for Salesforce AI while model-routing economics and an 8% year-to-date share decline leave the stock’s direction unresolved.
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)