What Changes
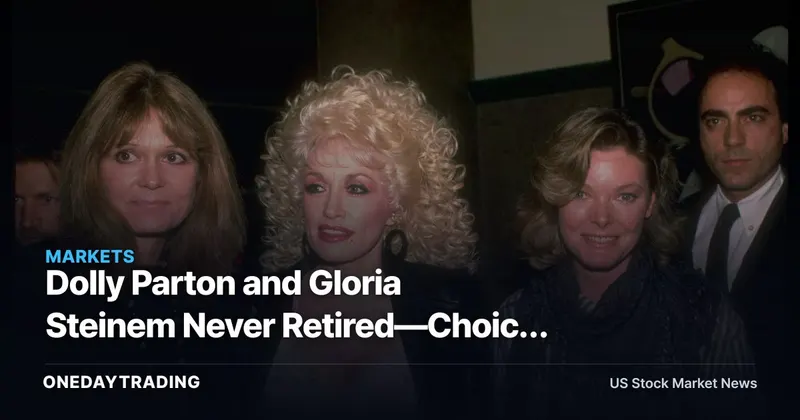
Dolly Parton and Gloria Steinem never officially retired because their work remained connected to passion and purpose, but their examples do not prove that working indefinitely suits everyone; the investable lesson is that retirement increasingly separates people with financial choice from people whose household balance sheets require another paycheck.
Retirement is the transition away from full-time employment, whether income afterward comes from accumulated savings or continued paid work. The source describes two paths under one label: people who keep working because the work itself matters, and people who continue because stopping is financially unavailable.
That difference changes behavior. A worker choosing projects can adjust time and workload; a worker dependent on wages remains exposed to job availability and the ability to keep working. For retirement planning, the decisive asset is not enthusiasm alone but control over when earned income ends.
By the Numbers
The source identifies two public figures—Dolly Parton and Gloria Steinem—who never officially retired, but provides no ages, income figures, savings balances or workforce statistics. Any broader claim about how many Americans work by choice versus necessity would therefore exceed the reported evidence.
The strongest conclusion is qualitative: the same decision can carry opposite financial meanings. Continued work can preserve optionality when savings already cover spending, but it becomes a balance-sheet vulnerability when future expenses depend on uninterrupted labor income.
Winners & Losers
- Retirement savers: Larger financial cushions increase the freedom to treat later-life work as optional.
- Financial-services providers: Longer and less uniform careers increase demand for planning around uncertain retirement dates, although the source names no company.
- Purpose-driven workers: Flexible work can extend engagement beyond full-time employment.
- Workers without savings flexibility: Health problems or lost employment can disrupt plans built on continued wages.
Risk Check
- Celebrity careers are unusually flexible and cannot represent typical working conditions.
- The source supplies no financial data linking purpose, savings and retirement outcomes.
- Never retiring can conceal overwork when personal identity becomes inseparable from employment.
- A plan dependent on future earnings fails if work ends earlier than expected.
Bottom Line
Dolly Parton and Gloria Steinem make lifelong work look purposeful, but the financially relevant divide is agency. Continuing by choice can preserve income and meaning; continuing by requirement concentrates risk in health and employability. The practical checkpoint is whether a household can fund spending if earned income stops before its preferred retirement date.
FAQ
Why did Dolly Parton and Gloria Steinem never retire?
CNBC reports that Dolly Parton and Gloria Steinem never officially retired and presents continued work as a way some people pursue their passions after leaving conventional full-time employment. The source does not provide personal financial details or a formal retirement timeline for either figure.
Is never retiring a good financial strategy?
Never retiring can extend earned income, but employment is not a guaranteed substitute for savings. If health or job availability interrupts work, a household relying on wages faces a sharper funding gap.
How can I tell whether working in retirement is a choice or necessity?
Working in retirement is optional when essential spending remains funded without employment income. Working becomes necessary when stopping wages would prevent the household from meeting its obligations.
📊 Analysis
Signal Neutral
Why The story highlights the flexibility and purpose of continued work but provides no market data or company-specific catalyst supporting a directional equity view.
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)