Summary
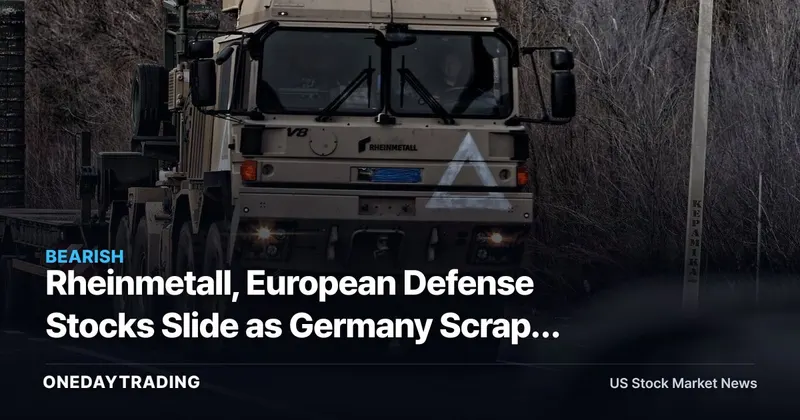
Germany scrapped its F126 naval frigate program, and the decision pushed Rheinmetall and other European defense names lower for a second straight session. The move matters less for one cancelled contract than for what it signals: procurement execution risk inside a rearmament story that markets had treated as a one-way bet.
The Full Story
The F126 frigate project was meant to be a flagship of Germany's naval buildup. Pulling it raises a direct question for investors who bought defense equities on the assumption that announced European spending converts cleanly into multi-year orders. Cancellations, delays and re-tenders sit between a defense budget headline and actual revenue, and this is a visible reminder that the conversion is neither automatic nor smooth.
Rheinmetall, the most-owned proxy for the European rearmament theme, fell for a second day alongside peers. The reaction is sentiment-driven as much as fundamental: Rheinmetall is primarily a land-systems and munitions supplier, so a naval program cancellation is not a core revenue hit for the company itself. The selling instead reflects a repricing of the entire group's order-flow certainty, with naval-exposed contractors carrying the more specific risk.
Structural Background
Europe's defense re-rating since 2022 has been built on the belief that elevated threat perception forces sustained, structural budget growth. That thesis remains intact at the spending-authorization level. The weak point is the procurement pipeline: shipbuilding in particular is capital-heavy, slow, and politically sensitive to cost overruns, making naval programs the most cancellation-prone link between budget and backlog.
Stock & Sector Ripple
- Rheinmetall (RNMBY): Theme bellwether; pressured on group-wide sentiment rather than direct F126 exposure, since its mix skews to ammunition and armored vehicles.
- Naval shipbuilders: Companies with frigate and surface-combatant exposure face the clearest read-through on program risk and re-tender uncertainty.
- U.S. naval primes — General Dynamics (GD), Huntington Ingalls (HII): Indirect; a European cautionary tale on naval execution can compress the multiple investors assign to long-cycle shipbuilding backlogs broadly.
- Diversified primes — Lockheed Martin (LMT), Northrop Grumman (NOC): Lower correlation; land, air and missile franchises are insulated from a single naval cancellation.
Bull vs Bear Scenarios
Bull case: the cancellation is a localized budgeting or specification problem, the underlying European spending commitment is unchanged, and any pullback in Rheinmetall is a discount on a still-rising order base. Bear case: this is the first crack in an over-extended momentum trade, where rich valuations priced perfect execution and procurement friction now drives a broader de-rating.
Investor Action Points
- Separate naval-exposed names from land and munitions suppliers; the F126 read-through is not uniform across the group.
- Track whether Germany re-tenders the frigate requirement or reallocates the budget — reallocation keeps the spending thesis alive, outright cuts do not.
- Watch Rheinmetall's next order-intake and backlog disclosure for evidence the theme rests on signed contracts, not announcements.
- Monitor whether the decline stays contained to European defense or spreads to U.S. shipbuilders, signaling a sector-wide repricing of program risk.
Market data check: RNMBY
RNMBY last traded near $214.24 (-19.55%). Our composite signal — blending price momentum and news flow — reads 🟡 neutral. Price momentum scores 5/100 (soft).
Data as of publication. Price via market feeds; for reference only, not investment advice.
📊 Analysis
Signal Bearish
Why A scrapped flagship naval program injects procurement-execution risk into the European rearmament trade, pressuring Rheinmetall and defense peers for a second day.
Tickers$RNMBY$GD$HII$LMT$NOC
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)