
What Investors Should Note About Min Byung-deok’s Tax-Deferral Proposal
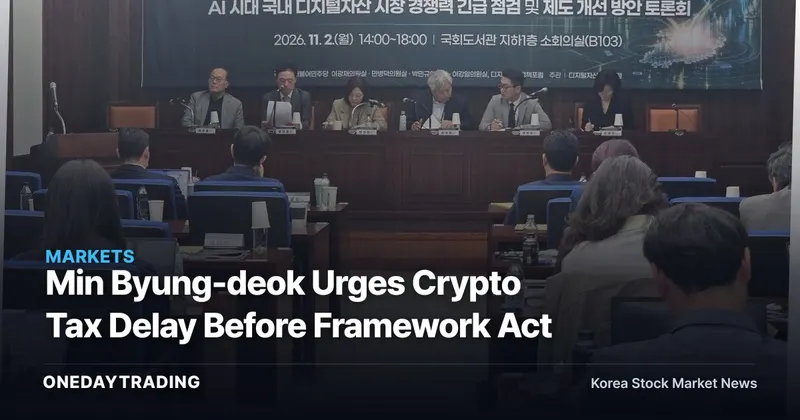
At a National Assembly Library forum on 2026-11-02, Min Byung-deok called for cryptocurrency taxation to be postponed. For investors, the key issue is not the proposal itself, but how the sequencing of taxation and the Digital Asset Framework Act is determined. The direction of the domestic digital asset market can be assessed only once the conditions and scope of the regulatory regime become clear.
The forum, reported by Yonhap News Securities, addressed the competitiveness of the domestic market, issues surrounding cryptocurrency taxation, and legal reforms for the era of the AI agent economy. The Digital Asset Framework Act refers to a foundational regulatory framework for the digital asset market, but the details and submission date of the government’s bill have yet to be confirmed.
The Policy Coalition Behind the National Assembly Library Forum
The event was hosted by the offices of Democratic Party lawmakers Lee Kwang-jae, Min Byung-deok, Park Min-gyu, and Lee Kang-il, and co-hosted and organized by the Digital Asset Policy Forum. Lim Jong-in argued that taxation should be postponed while related legislation and institutional frameworks are introduced promptly. He warned that allowing assets to continue leaving the domestic market could drive not only liquidity overseas, but also opportunities for industry, technology, and corporate growth.
Min Byung-deok said both tax fairness and market competitiveness must be considered, opposing a sequence in which taxation precedes the framework act. Lee Kwang-jae suggested that the bill could pass in January or February next year. This is not a confirmed schedule but a timeframe proposed by Lee, and whether the bill will actually pass remains undecided.
Meaning and Limitations of Kim Kyu-jin’s 700 Trillion Won Estimate
Kim Kyu-jin, CEO of Tiger Research, said about 700 trillion won in cryptocurrency had flowed overseas from South Korea over roughly five years since 2021. This figure represents gross outflows and does not deduct cryptocurrency that subsequently returned to the domestic market. It therefore should not be interpreted as net outflows, but as an estimate of the total volume of domestic funds routed through overseas channels.
Kim estimated that about 5 trillion won in trading fees went to overseas operators last year. The specific methodologies used to calculate the roughly 700 trillion won in outflows and 5 trillion won in estimated fees cannot be verified from publicly available information. While the two figures illustrate the concerns driving the policy debate, they cannot be directly translated into revenue or corporate valuations for domestic operators.
Market Confidence Conditions Raised Ahead of Taxation
Moon Kyung-ho, head of the Income Tax Division at the Ministry of Finance and Economy, said the government was carefully considering a reasonable approach that the public could accept and that could be implemented reliably in practice. Kim Woo-cheol, a professor of taxation at the University of Seoul, argued that the direction of cryptocurrency taxation should be discussed on the premise that a financial investment income tax is introduced. His position is that taxation should not be considered in isolation, but alongside the sequencing of other capital-gains tax regimes.
Moon Sung-hoon, a professor at Hallym University’s College of Business, said, “The goal of cryptocurrency taxation is not tax revenue but trust.” His argument is that clear implementation conditions and sequencing are necessary for investors and the market to anticipate the direction of regulation. Seo Na-yoon, head of the Financial Services Commission’s Virtual Asset Division, said internal discussions were underway on the need to revise certain financial industry laws after the Digital Asset Framework Act is enacted.
Transmission Channels to the Digital Asset Industry Sector
- If the tax deferral is confirmed and legislative discussions continue, the regulatory conditions for using the domestic market will become more concrete first. However, because neither the deferral nor its implementation date has been finalized, direct benefits to the industry sector cannot yet be quantified.
- Once the Digital Asset Framework Act is disclosed, the entities covered and the scope of revisions to financial industry laws will become key assessment criteria. Without specific legislative provisions, there is insufficient basis to identify particular listed companies as beneficiaries or casualties.
- Estimated overseas outflows and fees are the starting point for discussions about domestic market competitiveness. Their policy significance and the potential flow of assets back into the domestic market can be evaluated more precisely only after the calculation methodologies are verified.
Bullish Institutionalization Scenario and Delay Scenario
The bullish scenario would involve clarity on whether taxation will be postponed and a shift in the Digital Asset Framework Act debate toward concrete regulatory design. Investors should focus not on slogans, but on the sequencing of taxation, implementation conditions, and the scope of revisions to financial industry laws. If regulatory predictability continues to improve, discussions about domestic market competitiveness could move into the implementation stage.
The bearish scenario would involve continued delays without the bill’s contents or submission date being determined. If the claims and figures presented at the forum do not lead to actual legislation, there will be no basis for translating policy expectations into prices or corporate earnings. Any impact of the forum’s conclusions on legislation and policy also remains beyond what can currently be confirmed.
Investment Criteria to Monitor Through January–February Next Year
- Confirm whether cryptocurrency taxation will be postponed and the finalized implementation date.
- Monitor whether discussions on passing the bill actually proceed in January or February next year, as mentioned by Lee Kwang-jae.
- Confirm the specific contents and submission date of the government’s Digital Asset Framework Act bill.
- Check whether the Financial Services Commission discloses the scope of revisions under discussion for certain financial industry laws.
What is currently known is the argument that institutionalization should precede taxation and the scope of discussions at the National Assembly forum. What remains unknown is whether the deferral will be confirmed, the details of the framework act, and the impact on individual companies’ profits and losses. The next inflection point is not a price move, but public deliberation on the bill and confirmation of the taxation schedule.
This article was automatically summarized and analyzed based on the original news report. View the original article (Yonhap News Securities)