What the $38.1 Billion Estimate Means for Defense Investors
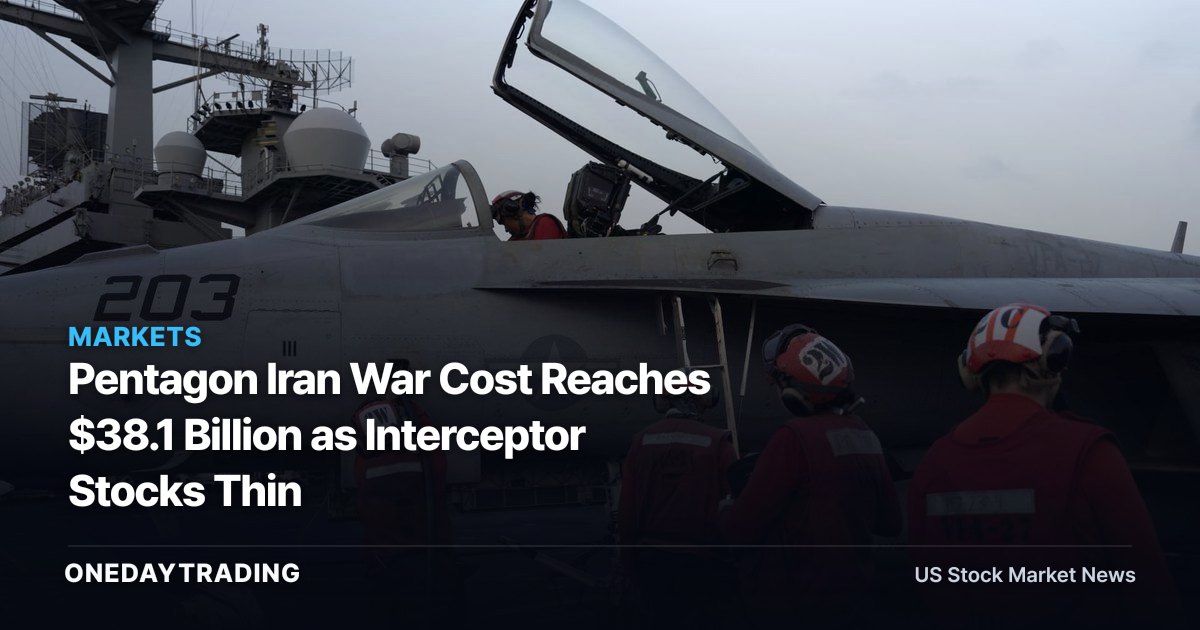
Defense stocks face a supply-and-capacity question after the Congressional Budget Office reported Tuesday that the U.S. war with Iran cost the Pentagon an estimated $38.1 billion through Aug. 1. More than half of that amount went to replacing missiles and other munitions, while the United States consumed as much as two-thirds of its missile-defense interceptors since June 2025. The immediate read-through is not a confirmed earnings result for any listed contractor; it is evidence of a multi-year replenishment requirement whose funding, production capacity and timing are still unspecified.
President Donald Trump launched the war on Feb. 28. CBO estimated that each additional month of fighting could add $2 billion to $3 billion to Pentagon costs. That range makes duration the key variable for defense budgets, but the report does not provide an exact monthly figure or a rebuilding plan.
Where the Pentagon Bill Came From
The munitions line dominates the estimate. CBO said more than half of the $38.1 billion total came from replacing missiles and other munitions used in the conflict. Increased flying hours added $10.4 billion through Aug. 1, and higher fuel prices added $2.7 billion. For investors, those categories transmit through different channels: weapons demand depends on production orders and replenishment appropriations, while flying and fuel costs reflect operating intensity rather than a durable equipment backlog.
A separate Pentagon estimate, covering costs through June 29, put the total at $33.4 billion. It comprised $7.4 billion in incremental operating costs, $22.3 billion for expended munitions and $3.7 billion in equipment losses. The gap between the two dates and methodologies means the figures should not be treated as a single audited series, but both accounts point to munitions as the largest component.
The Defense Department inspector general described the pace of weapons use as creating “strategic inventory shortfalls.” CBO warned that rebuilding the Department of Defense interceptor inventory would probably take at least five years, even if production increased. That timeline turns a wartime drawdown into a capital-cycle issue: demand may be visible now, while deliveries depend on motors, explosives, propellants and skilled workers.
Interceptor Capacity Is the Binding Constraint
Missile-defense inventories are a stock, not a flow. Consuming as much as two-thirds of interceptors since June 2025 reduces the available buffer for another engagement before new production arrives. CBO called the risk “especially problematic” in a conflict with an adversary possessing large numbers of ballistic and cruise missiles, citing China and a potential conflict over Taiwan.
The United States helped defend Israel against Iranian attacks, linking the inventory drawdown to an operational mission beyond the immediate battlefield. That relationship does not establish which companies would receive contracts or when. It does establish the mechanism investors should track: replenishment only becomes revenue when procurement decisions, production capacity and deliveries line up.
The inspector general’s supply-chain findings add friction to that process. Shortages of solid rocket motors, explosives, propellants and skilled workers complicate efforts to replenish stockpiles. A larger authorization therefore would not automatically produce a near-term shipment surge. The relevant evidence will be contract awards, production schedules and delivery milestones, none of which the supplied reports quantify.
Equipment Losses Extend the Rebuild Beyond Missiles
Iranian strikes damaged or destroyed hundreds of buildings and structures at bases across eight Middle Eastern countries. The reported aircraft losses included four F-15E fighter jets, one F-35A, seven KC-135 refueling aircraft, seven helicopters and more than 30 drones. The exact number of damaged structures and aircraft is not provided, so the disclosed list should be read as a reported subset rather than a complete toll.
Replacement economics vary sharply by platform. The U.S. Air Force puts the F-35A cost at as much as $92 million per plane, while the F-15E cost $31.1 million in 1998 and the aircraft is no longer produced. Those figures illustrate why equipment losses can create different procurement paths: a current platform may connect to an existing production line, whereas an out-of-production aircraft may require a different sustainment or replacement decision. The facts do not identify the eventual funding source.
Damage also reached the diplomatic network. The State Department incurred $79.2 million in evacuation and other contingency costs, while damage to diplomatic sites in Iraq, Kuwait, Saudi Arabia and the United Arab Emirates was calculated at $184 million. These amounts broaden the fiscal footprint beyond Defense Department procurement, but they do not by themselves indicate a listed-company revenue change.
Key Debates for the Defense Sector
- Replenishment versus readiness: The five-year rebuilding estimate implies a prolonged inventory-management problem, yet the reports do not state how quickly production can be expanded or how readiness priorities will be ranked.
- Appropriations versus execution: More than half of the cost came from expended munitions, but no rebuilding plans or funding sources were provided. Authorization would be an intermediate step, not proof of delivered revenue.
- War duration: CBO’s $2 billion-to-$3 billion additional monthly range makes continued fighting a material budget variable. The exact incremental cost within that range is unknown.
- Strategic allocation: CBO’s China-and-Taiwan scenario frames interceptor inventories as a contingency asset. That does not forecast a conflict; it identifies the risk of entering one with reduced stocks.
What to Watch Next
- Procurement documents: Look for Defense Department contract awards and budget requests tied to missile-defense interceptors, missiles and other expended munitions.
- Industrial inputs: Track disclosures on solid rocket motors, explosives, propellants and skilled-worker availability, the specific constraints identified by the inspector general.
- Inventory timeline: Compare any new production guidance with CBO’s estimate that rebuilding could take at least five years, rather than assuming an immediate normalization.
- Conflict duration and operating costs: Any extension beyond Aug. 1 should be assessed against CBO’s $2 billion-to-$3 billion monthly range, while separating operating expenses from replacement orders.
Defense Outlook: Demand Signal, Execution Risk
The reports create a clear but incomplete investment signal. A $38.1 billion Pentagon cost through Aug. 1, a $22.3 billion munitions component in the June 29 estimate and consumption of as much as two-thirds of interceptor stocks all point to substantial physical demand for replenishment. That is the constructive case for the defense supply chain.
The countercase is execution. Production bottlenecks, a rebuilding horizon of at least five years and undisclosed funding plans can delay or reshape any benefit. Aircraft and base losses add requirements, but the source does not identify company awards, margins or delivery schedules. Investors should therefore treat the event as a high-impact defense-capacity development, with contract evidence and budget execution—not the headline cost alone—as the next confirmation points.
📊 Analysis
Signal Neutral
Why The cost and inventory data create fiscal and operational pressure, but the facts do not establish a direct earnings effect for any listed company.
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)