Summary
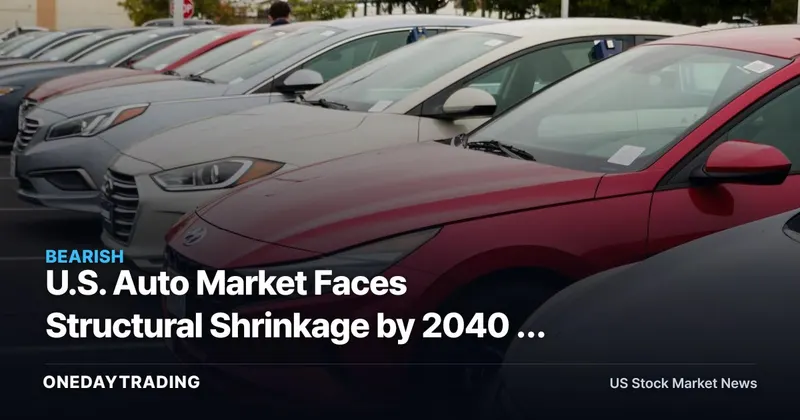
The U.S. auto industry is selling fewer cars, and at least one major forecaster now argues the slide is structural — not cyclical — and will compound through 2040. The read-through for investors is blunt: capacity decisions being locked in today are priced against a market that the supply side may be systematically overestimating.
The Full Story
The distinction that matters here is not between a good quarter and a bad one — it is between a demand dip that responds to rate relief and an ownership model that is quietly, permanently contracting. When a forecaster frames the current environment as a convergence of forces rather than a temporary headwind, the implication is that the traditional policy levers available to automakers — incentive packages, financing deals, production cuts timed to a recovery — are solutions to a problem that no longer describes the situation. The market is not pausing; it is repricing.
The structural forces compressing long-run demand share a common mechanism: each one separates transportation demand from personal-vehicle ownership. Ride-sharing platforms, shifting work patterns, demographic change in license-acquisition rates among younger cohorts, and the eventual deployment of autonomous mobility all pull in the same directional. They do not need to arrive simultaneously to shrink the baseline — their timelines overlap enough that the cumulative effect compounds across a planning horizon that reaches well into the next decade and beyond. That is what makes this a capital-cycle problem, not a sales-mix problem.
Structural Background
Legacy automakers — GM, Ford, Stellantis — are mid-cycle through some of the largest plant retooling programs in their histories, converting ICE production lines to EV architecture at cost. The economics of that retooling are built on an assumption: that the addressable market is large enough, at sufficient utilization, to amortize the capital over time. A structurally smaller market does not just reduce revenue; it attacks plant utilization, which is where fixed-cost leverage lives. Industries that have mispriced a structural demand ceiling have historically consolidated hard and fast once the overcapacity thesis becomes consensus — and the exit cost for the last mover is always the worst.
Stock & Sector Ripple
- GM — Largest U.S.-market volume exposure among domestic OEMs. A permanent demand ceiling compresses the utilization math on new EV plants before those facilities reach target output, pressuring return on invested capital timelines.
- Ford (F) — Ford Blue (ICE) is cross-subsidizing Model e (EV) losses; a shrinking total market reduces the revenue pool available for that internal transfer, tightening the path to EV profitability.
- Stellantis (STLA) — Truck- and Jeep-heavy mix buys near-term pricing insulation, but long-cycle capacity commitments carry the same structural demand risk as peers.
- Tesla (TSLA) — Software and energy segments provide partial insulation, but automotive unit economics remain volume-dependent; market-share gains compound less powerfully against a shrinking total addressable market.
- Tier-1 suppliers (MGA, LEA) — Doubly exposed: OEM volume risk plus accelerating ICE-component obsolescence. Suppliers that have not yet repriced long-cycle ICE platform contracts face the sharpest margin risk in a structural-decline scenario.
Bull vs Bear Scenarios
Bear: If the structural thesis holds, excess capacity — already a chronic industry pathology — deepens. Pricing discipline erodes as producers fight for share in a contracting pool. Fixed-cost structures built for a larger market become permanent headwinds, and OEM equity multiples reprice toward capital-intensive, slow-growth industrials rather than the transformation story the market is currently paying for.
Bull: The U.S. remains far less densely urbanized than Europe or Asia, sustaining personal-vehicle economics longer than headline structural models imply. Autonomous vehicle deployment has consistently slipped its own forecast timelines — every year of delay preserves the traditional ownership baseline. A prolonged consumer credit normalization could also cap ride-share penetration by limiting platform subsidization. None of these factors reverse the thesis; they slow it.
Investor Action Points
- Monitor U.S. SAAR monthly — a trend that stays below the prior-cycle baseline even through rate normalization would be the clearest early confirmation that this is structural, not cyclical.
- Watch OEM plant-utilization disclosures at quarterly earnings; sub-80% utilization at new EV facilities is the earliest concrete signal that capex assumptions are running ahead of demand.
- Track any revisions to long-cycle capital plans at GM and Ford earnings — guidance cuts on new-plant investment would signal that management is internalizing the demand ceiling ahead of consensus.
- This is a slow-burn thesis with a 2040 horizon; near-term stock catalysts will still be SAAR, incentive spend and rate sensitivity — but structural position sizing should reflect a headwind that compounds quietly through every planning cycle.
Market data check: GM
GM last traded near $78.9 (+1.02%). Our composite signal — blending price momentum and news flow — reads 🟡 neutral. Price momentum scores 58/100.
Data as of publication. Price via market feeds; for reference only, not investment advice.
📊 Analysis
Signal Bearish
Why A structural demand-contraction forecast directly undermines the volume assumptions underpinning current OEM capital expenditure programs, compressing utilization and return-on-invested-capital timelines across the domestic auto sector.
Tickers$GM$F$STLA$TSLA$MGA
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)