AI’s repricing moves from excitement to proof
AI-linked equities are entering a phase in which investors must test spending, orders and cash generation rather than simply extrapolate technological promise. CNBC reported that the narrative has shifted from predominantly optimistic expectations toward risks, public unpopularity and uncertainty over order backlogs beyond a few quarters. For semiconductor companies, the immediate evidence is harsh: shares were already 20% below their June highs before sliding another 4% on Monday.
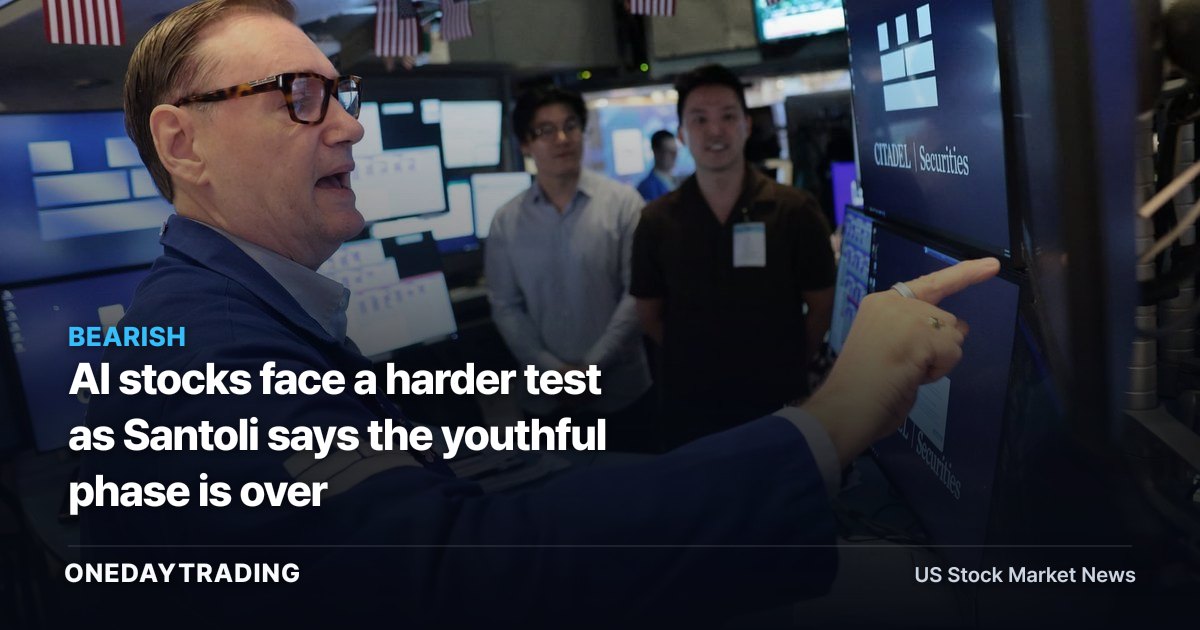
Mike Santoli described this change as the end of “the youthful phase of AI.” That phrase does not mean the technology stops advancing. It means the market is assigning greater weight to execution, timing and durability, while giving less credit to projections that depend on a long chain of future demand.
Valuation has already absorbed part of the disappointment
The S&P 500 technology sector’s forward price-to-earnings multiple fell from 29 to 21 over the past year. That contraction shows the tape has already reduced the premium attached to expected growth. The next question is whether earnings can catch up with the lower multiple, or whether estimates tied to semiconductor demand and 2027 profits still assume too much uninterrupted expansion.
The source says projections of order backlogs beyond a few quarters are now suspect. That matters because a long-dated backlog is often treated as evidence that today’s capacity spending will produce tomorrow’s revenue. If customers delay, resize or renegotiate deployments, the market can challenge both the earnings estimate and the valuation assigned to the supplier.
Public opposition adds a separate uncertainty. Data centers are described as having a lower approval rating than Congress, making the politics of new construction part of the investment case. The article does not establish a definitive change in AI policy, model training or computing-capacity demand, so investors cannot treat resistance as proof that spending will fall.
Microsoft, Alphabet and Meta get a slowdown cushion
Microsoft, Alphabet and Meta are identified as the major platforms conducting most of the AI capital expenditure. Their Monday share performance offered a possible silver lining: a slower buildout could give these companies time to pause before accelerating capital raising and deployment again. That interpretation is conditional. A pause may protect free cash flow, but it could also signal that expected demand is arriving more slowly.
The market’s preference has recently moved toward businesses showing copious free cash flow. The VictoryShares Free Cash Flow ETF, which contains software, healthcare and energy stocks, tracked the Mag 7-dominated S&P 500 for two years before outperforming it in the past few months. The rotation suggests investors are paying closer attention to cash conversion and price discipline when AI enthusiasm no longer supplies an easy growth premium.
For platform companies, the critical transmission mechanism is capital intensity. Spending on data centers and related infrastructure must eventually support durable monetization. The facts supplied here do not provide company-level revenue, margin or utilization data, so the appropriate test is whether subsequent disclosures demonstrate that investment is converting into cash flow rather than merely expanding the asset base.
Rates make the valuation hurdle higher
CNBC described the Federal Reserve as poised to begin lifting interest rates while 10-year Treasury yields top 5%. That combination matters for long-duration technology stocks because higher discount rates reduce the present value of profits expected further into the future. It also raises the return investors can seek from bonds and cash, increasing the opportunity cost of holding expensive growth shares.
The article draws an echo with June 1999, when the Fed began hiking as 10-year Treasurys reached 6%, after three rate cuts late the prior year. Policymakers then raised rates by a full percentage point into early 2000 and added another 75 basis points afterward. Santoli cautions against treating the periods as identical: yields in 1999 had declined from 7%-8% five years earlier, while the current comparison is with yields that had risen from 1% over the past five years.
Other market conditions also differ. Corporate tax rates were 35% in 1999 versus 21% now, and retail-brokerage firms charged $15 per trade then. Those contrasts limit the usefulness of a simple repeat-of-1999 argument. They do not remove the present sensitivity of technology multiples to rates above 5%.
Market breadth shows rotation, not a clean break
The S&P 500 fell 0.5% on Monday even as 10% of its constituents dropped 4% or more and about 10% rose at least 4%. Since June 1, the index has gone sideways and remained within 3% of its record high; it has spent nearly all the time since Aug. 4 inside that day’s rally range. These figures describe violent internal rotation rather than a decisive index trend.
That pattern can support a rebound if oversold conditions build, but it can also conceal concentration risk. Bank of America’s weekly tracking of wealthy private clients shows equity exposure at quarter-century highs, with bonds and cash near historic lows. Investors have allowed stock allocations to rise with the market instead of rebalancing, leaving portfolios vulnerable if the rotation turns into broader de-risking.
John Kolovos of Macro Risk Advisors said, “Bullish sentiment is moderating but has yet to reach contrarian extremes,” despite weak beta performance, a VIX spike and more stocks falling below their 50-day moving averages. Sentiment has cooled, but the indicator does not establish that selling pressure is exhausted.
What can confirm or reject the new AI regime
The bullish case is that the purge of high-momentum AI hardware and related industrial stocks has removed speculative excess. A less aggressive market could let Microsoft, Alphabet and Meta deploy capital at a more measured pace while cash-flow-oriented sectors retain leadership. If orders remain firm and policy does not materially restrict construction, the current reset could become a valuation digestion rather than a collapse in demand.
The bearish case is a chain reaction: public resistance delays data-center approvals, long-term backlog assumptions weaken, semiconductor earnings projections for 2027 are cut, and Treasury yields above 5% pressure the 21 forward P/E multiple further. The article does not determine which path will prevail or whether the narrative shift will persist.
Investors should therefore monitor the next available company disclosures for three items: evidence that AI capital spending is producing cash flow; order visibility beyond only a few quarters; and any change in stated plans for model training or computing capacity. At the market level, track whether the S&P 500’s sideways range since June 1 resolves alongside Treasury yields above 5%. Those checkpoints can distinguish a temporary sentiment reset from a more durable reassessment of AI economics.
Related signals beyond the megacaps
- Semiconductors: The 20% pre-Monday decline and subsequent 4% slide show how quickly assumptions tied to future AI capacity can transmit into hardware valuations.
- Microsoft, Alphabet and Meta: As the principal AI-capital-expenditure platforms identified by the source, they may benefit from a slower deployment pace through improved spending discipline, while facing the risk of weaker demand.
- VictoryShares Free Cash Flow ETF: Its recent outperformance versus the Mag 7-dominated S&P 500 reflects a market preference for software, healthcare and energy companies screened for free-cash-flow characteristics.
- SpaceX and Bending Spoons: SpaceX’s June 2026 IPO and Bending Spoons’ June Nasdaq listing illustrate how new public-market narratives are being judged amid a more skeptical technology tape. The Wall Street Journal’s forensic-accounting examination of Bending Spoons questioned alternative earnings metrics that exclude amortization and its customer retention.
Forward markers for investors
- Watch the next earnings and guidance updates for semiconductor-dependent companies, especially assumptions supporting 2027 earnings projections.
- Compare announced AI capital expenditure with disclosed cash-flow outcomes at Microsoft, Alphabet and Meta.
- Track data-center approval developments and any stated changes in AI policy, model training or computing-capacity plans; the supplied evidence does not provide a definitive outcome.
- Observe whether breadth improves from the current pattern of roughly 10% of S&P 500 constituents moving 4% or more in opposite directions, and whether the index breaks its range since June 1.
📊 Analysis
Signal Bearish
Why Investor enthusiasm is moderating as semiconductor losses, lower technology-sector multiples, public resistance and uncertain long-term backlogs challenge AI-linked assumptions.
Tickers$MSFT$GOOGL$META$NVDA
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC)