Nirmala Sitharaman’s Liquidity Message
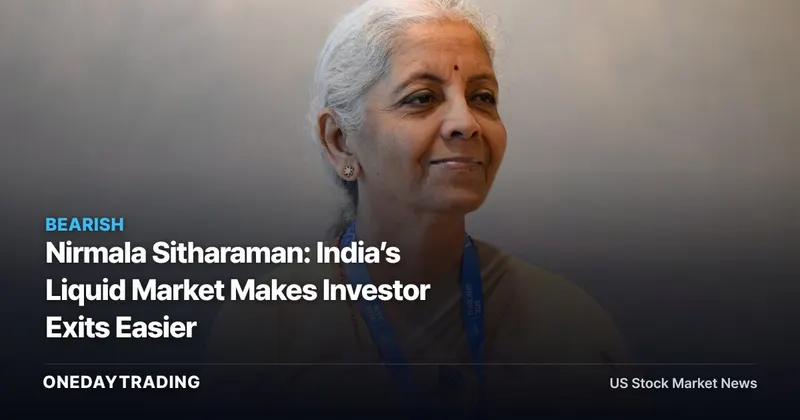
Nirmala Sitharaman has identified the central tension confronting Indian equities: a liquid market makes foreign investor exits easier even when the economy’s fundamentals are “fine.” For international investors, the immediate signal is bearish because foreign portfolio selling and weaker benchmark indexes are occurring alongside persistent domestic demand. Liquidity is cushioning the act of selling; it is not evidence that the selling pressure has ended.
CNBC Markets reported that India’s key benchmark indexes have slipped nearly 12% since January, citing LSEG data. The finance minister separately identified fuel, fertilizer and the flow of capital as major economic risks for 2027. Those risks matter through different channels, though the supplied evidence does not specify their future effects.
What Easier Equity-Market Exits Actually Mean
Equity-market liquidity is the ability to buy or sell shares with relative ease. Sitharaman’s point concerned that market function: “Because of the ease of liquidity, ease of availability, people are even exiting easily.” The article was corrected to clarify that she was discussing ease of exit, not blaming excess liquidity for stock-market underperformance.
That distinction is essential. A liquid market can accommodate transactions by departing investors and incoming domestic capital at the same time. It does not, by itself, establish why India’s key benchmark indexes declined or prove that liquidity caused foreign portfolio sales.
NSDL data show that foreign portfolio investors have sold more than $33 billion of direct Indian equities so far this year. The precise end date covered by “so far this year” is not stated, so the figure should be read as a reported flow measure rather than a fixed full-period total.
Domestic Funds Absorb Supply as Foreign Investors Sell
The counterweight is domestic capital. Indian equity mutual funds have recorded net inflows every month since March 2021, according to the Association of Mutual Funds in India. That record indicates recurring demand during a period in which foreign portfolio investors have been able to reduce exposure.
The coexistence of foreign selling and domestic inflows explains why liquidity can be both a market strength and an investor risk. Ready buyers can support transaction capacity, while sellers can use that capacity to exit. The facts establish both flows, but they do not quantify how much domestic mutual-fund demand offset foreign sales or determine the resulting index effect.
For the tape, the key divide is between market function and market direction. India’s equity market can remain accessible and active even as its key benchmark indexes fall. Investors therefore need to track who is supplying capital, who is withdrawing it and whether the balance changes—not treat liquidity alone as a directional signal.
Indian IPOs Show Who Has Monetized Liquidity
The primary-market figures make the exit mechanism tangible. EY reported that Indian initial public offerings raised $60.4 billion between 2021 and 2025. Existing holders received $37.7 billion, equal to 63% of total proceeds, by selling shares to the public during that period.
Those figures show that a large share of IPO proceeds enabled existing owners to monetize holdings rather than directing all proceeds elsewhere. This does not establish that such exits were harmful to later market performance. It does show why investors should examine who receives the proceeds whenever the market’s liquidity is presented as an unqualified strength.
The analytical question is whether new public demand continues to accommodate sales by existing holders without weakening the broader capital-flow balance. The supplied facts document the scale of past proceeds and the recipients, not the pricing, subsequent returns or future IPO pipeline.
Goldman Sachs Maps the Regional Capital Shift
Regional index weights provide another view of the pressure. In its Oct. 8 report, Goldman Sachs put Taiwan at a 29% weighting and Korea at a 22% weighting in the MSCI Asia Pacific ex-Japan index. India’s share had declined from 19% a few years ago to 10%, according to the same report.
This comparison matters because index weighting describes India’s reduced position within that specific regional benchmark while Taiwan and Korea occupy larger shares. It does not prove that a single theme caused every portfolio decision. Sitharaman described capital moving toward AI and the U.S. as “a concern,” while also saying India had not received the same kind of AI investment flowing into other jurisdictions.
She said India would not be “hurt” by spillover if the global AI rally’s bubble burst and described the country as “no longer a laggard” in frontier technology. The evidence supplied does not quantify India’s technology investment or connect it to named listed companies, so a company-level earnings conclusion would exceed the available facts.
Bull and Bear Cases for Indian Equities
Bull case: Monthly net inflows into Indian equity mutual funds have continued since March 2021, providing a recurring domestic source of demand. Sitharaman also characterized the economy’s fundamentals as “fine.” If domestic inflows persist while foreign sales moderate, the imbalance visible in current flow data could become less severe.
Bear case: Foreign portfolio investors have sold more than $33 billion of direct Indian equities so far this year, India’s key benchmark indexes have fallen nearly 12% since January, and its MSCI Asia Pacific ex-Japan weighting stands at 10% in the Oct. 8 Goldman Sachs report. Continued foreign selling alongside a lower regional weight could keep capital flows as the central market risk.
Neither case resolves the 2027 risks around fuel, fertilizer and capital flows. Their specific future effects are not given, which prevents a defensible forecast for company revenue, margins or sector leadership. The investable conclusion is narrower: domestic demand supports liquidity, while foreign sales and regional reweighting keep direction uncertain and presently tilted negative.
Investor Checkpoints After Sitharaman’s Remarks
- Foreign sales: Check the next NSDL reading to see whether direct Indian equity selling continues beyond the reported total of more than $33 billion so far this year.
- Domestic demand: Monitor the next Association of Mutual Funds in India release for whether monthly net inflows extend the sequence that began in March 2021.
- Benchmark direction: Compare the next LSEG index reading with the nearly 12% decline since January; the source does not state a more precise starting date.
- Regional allocation: Watch subsequent Goldman Sachs or MSCI information for changes from India’s 10% share of the MSCI Asia Pacific ex-Japan index and from Taiwan’s 29% and Korea’s 22% weights in the Oct. 8 report.
The next decisive evidence will come from flows rather than rhetoric. If domestic mutual-fund inflows remain steady and foreign portfolio selling slows, liquidity will look more like resilience. If foreign exits continue while India’s regional weighting remains compressed, the same liquidity will keep functioning as an efficient route out.
📊 Analysis
Signal Bearish
Why Persistent foreign selling, weaker benchmark indexes and India’s reduced MSCI weighting create a negative market signal despite steady domestic mutual-fund inflows.
This article was independently written by OneDayTrading from public reporting. Read the original (CNBC Markets)